
Insurance claims are fundamentally processed on the operational assumption that every reported loss is genuine and falls squarely within the governing parameters of the policy contract. However, when submitted information appears inconsistent, incomplete, or mathematically unusual, an insurance carrier will routinely conduct deeper investigative reviews before making a final decision to pay, adjust, or deny a claim. These rigorous reviews form a core component of the industry's broader effort to detect insurance fraud and verify property and casualty losses with precision.
Modern anti-fraud systems are by no means limited to simplistic automated software filters. Insurance companies routinely synthesize historical claims data, underlying policy terms, photographic evidence, contractor repair records, recorded interviews, external databases, and human investigative expertise. The exact operational workflow varies significantly depending on the insurer, the line of insurance, state statutory regulations, and the unique factual backdrop of the claim. Crucially, having a claim flagged for potential anomalies does not automatically mean that fraud has occurred, as unusual characteristics frequently have entirely legitimate, innocent explanations.
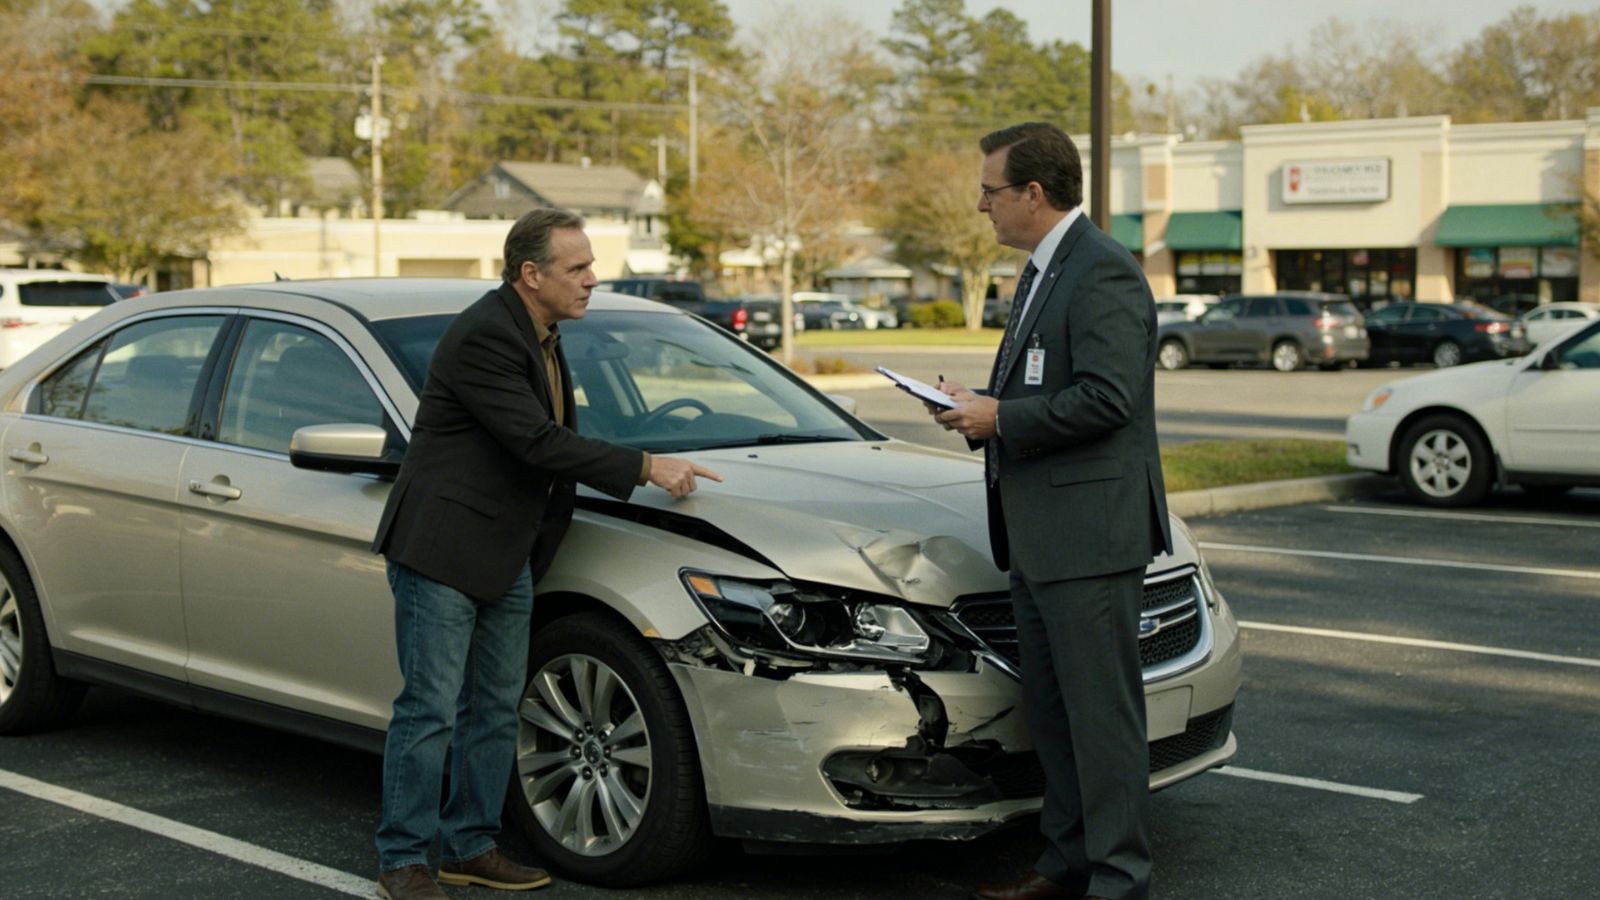
Insurance fraud manifests in many forms, ranging from deliberately fabricated property losses and exaggerated repair estimates to staged vehicular accidents and material misrepresentations during the underwriting or claims process. The National Association of Insurance Commissioners notes that insurance fraud remains a significant financial concern for both carriers and consumers, prompting state insurance departments and law enforcement agencies to maintain specialized investigative units. Unchecked fraud ultimately distorts loss ratios, driving up premium costs for honest policyholders across the entire insurance market.
For a claims adjuster, the primary objective during a review is not simply to penalize something that looks unusual, but to determine whether the reported circumstances align logically with objective physical evidence and policy parameters. A severely damaged automobile, for instance, requires a comprehensive cross-examination of the reported accident dynamics against high-resolution photographs, professional body shop estimates, vehicle history reports, and independent witness statements.
This operational distinction matters deeply because legitimate claims frequently contain ordinary inconsistencies. A stressed policyholder may mistakenly recall the exact date a storm hit, misplace an original purchase receipt, approximate the age of a destroyed household appliance, or describe a chaotic incident with minor narrative variations. An automated algorithmic flag or a routine request for clarification should therefore never be misinterpreted as an immediate accusation of wrongdoing.
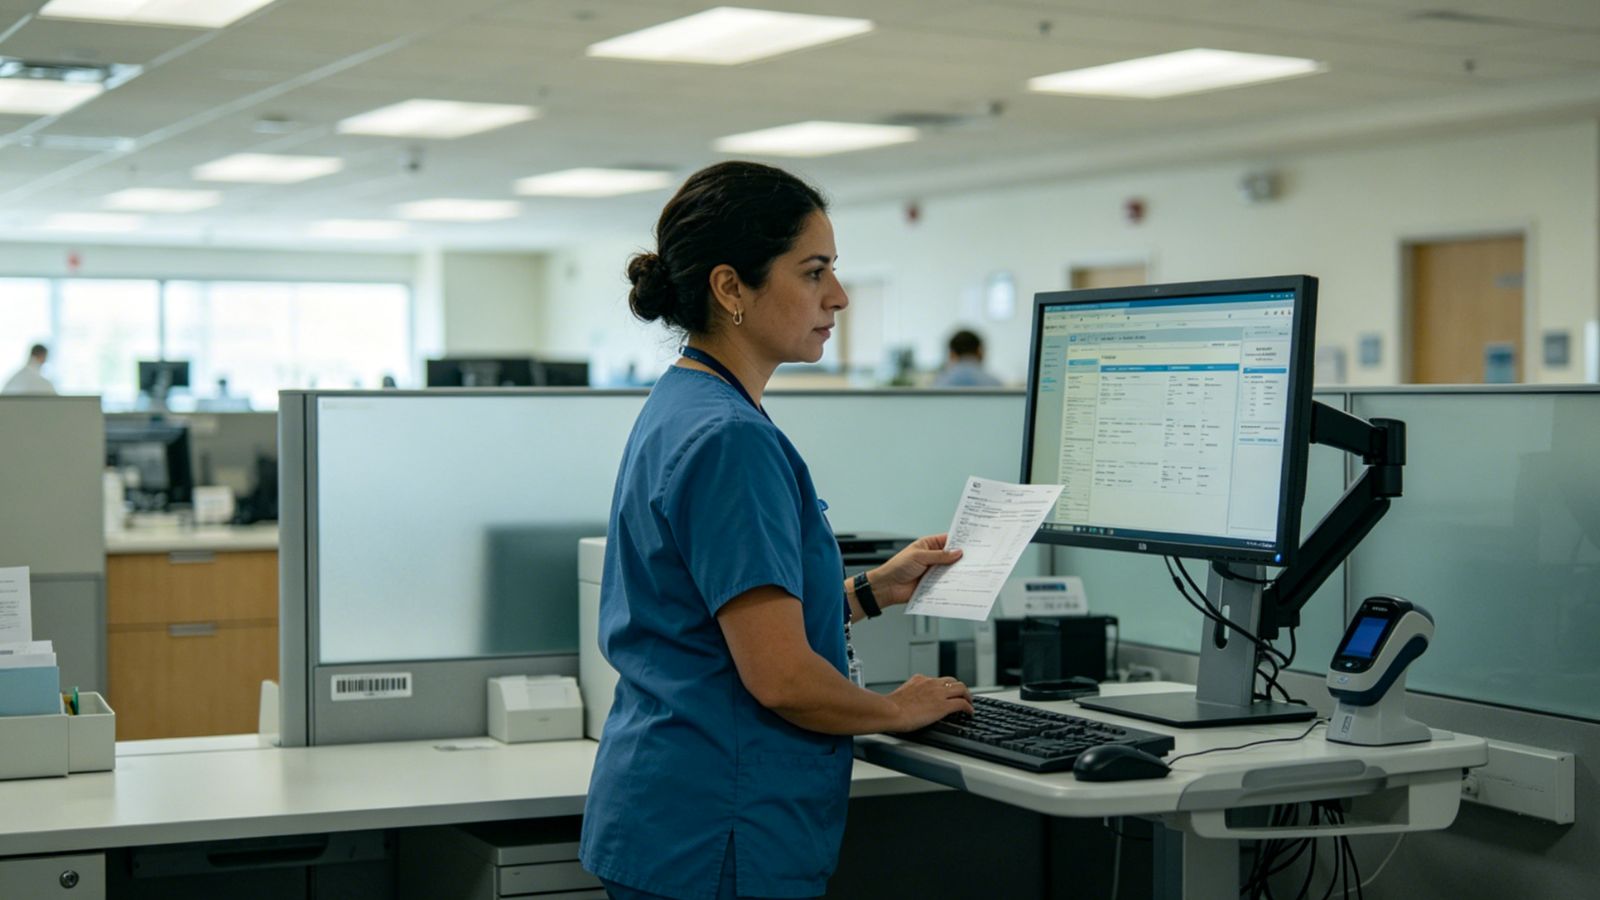
Insurers deploy sophisticated automated systems designed to screen incoming files and identify claims that warrant a closer, more granular examination. These proprietary screening platforms analyze thousands of data points associated with a specific claim, comparing them against statistical patterns extracted from millions of historical claims and underwriting records.
Potential indicators that trigger secondary scrutiny often include unusual timing anomalies, stark discrepancies between separate evidentiary documents, repeated loss histories involving similar circumstances, or narrative details that fail to align with the laws of physics or local weather data. Technology excels at uncovering subtle relational patterns that human adjusters would struggle to spot manually. Comprehensive claims databases aggregate historical loss data, prior insurance applications, property transfers, and vehicle registration records. When multiple isolated data points conflict, investigators step in to examine the underlying records.
Nonetheless, these digital detection systems function primarily as screening tools rather than definitive decision-makers. Skilled human investigators are always required to determine why an apparent data anomaly exists and whether it holds any substantive relevance to the validity of the claim.
Once a claim is routed for specialized investigation, the insurer seeks to assemble a watertight factual record establishing precisely what happened, when the event occurred, and the true financial extent of the resulting damage. The specific categories of evidence examined depend heavily on the class of insurance involved.
For residential property claims, investigators routinely review high-resolution photographs, independent inspection reports, contractor repair estimates, purchase invoices, historical home inventories, and pre-loss maintenance records. They meticulously cross-reference the physical damage patterns against the reported cause of loss, such as comparing wind-shear data with roof shingle displacement.
Automobile claims involve inspecting vehicle damage photos, police collision reports, body shop tear-down estimates, telematics data, and driver statements. In complex liability or collision cases, forensic engineering analysis or accident reconstruction experts may be retained. For health and disability insurance, verification focuses on clinical medical records, billing codes, provider credentials, and strict policy necessity guidelines to confirm that services were actually rendered and properly documented.
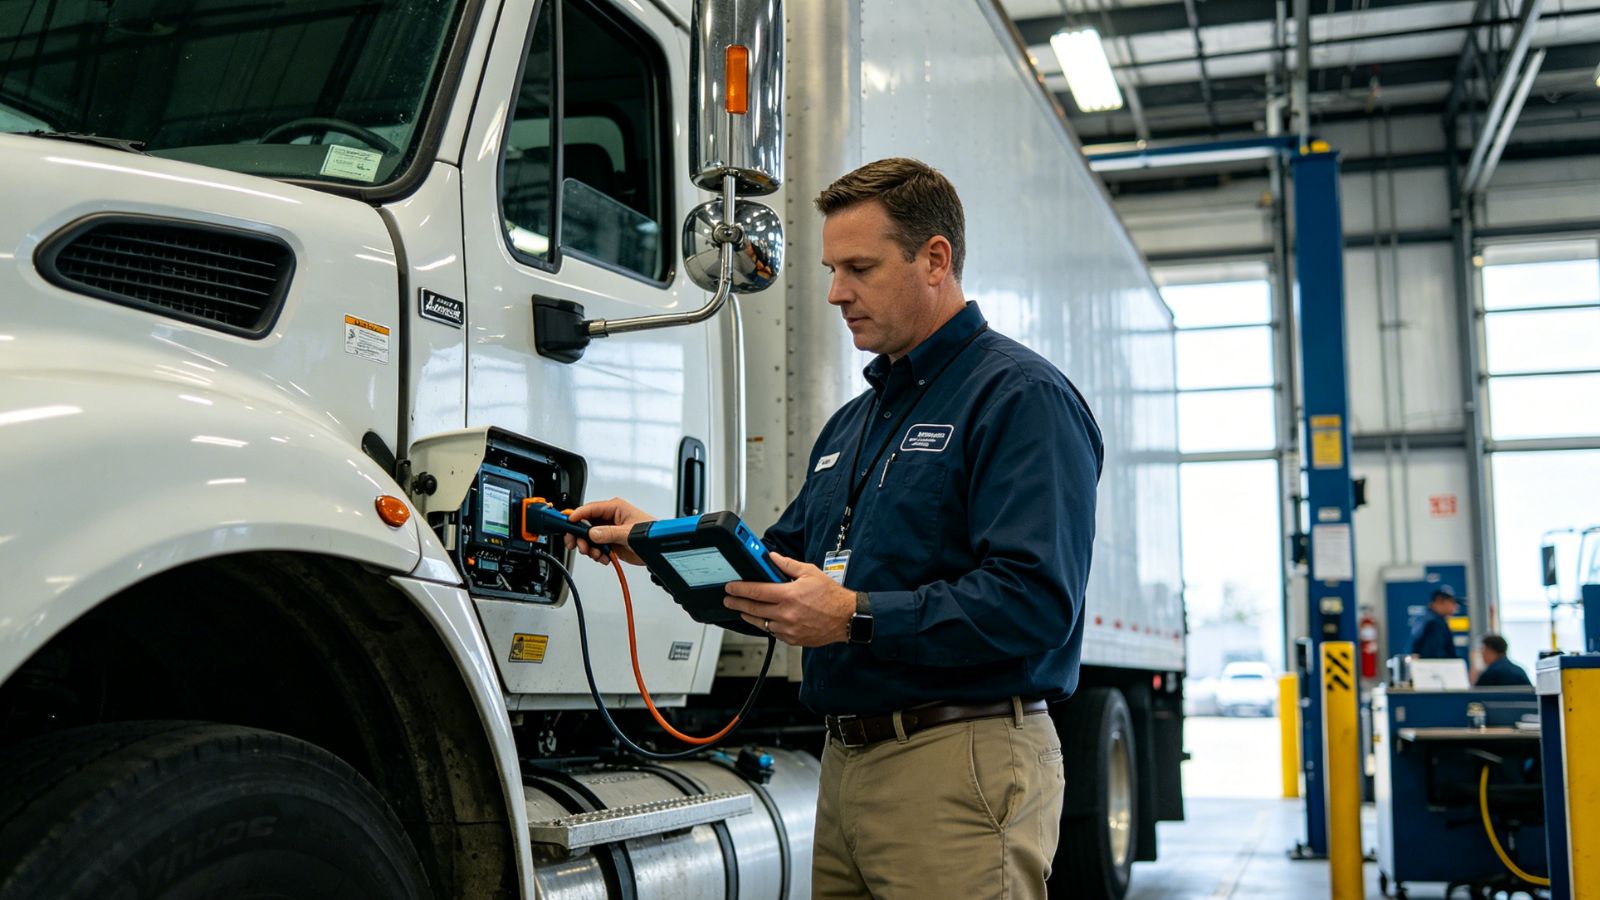
Many insurance carriers maintain dedicated Special Investigation Units (SIUs) staffed by experienced investigators trained to handle complex files involving potential fraud or severe discrepancies. Organizations like the National Insurance Crime Bureau collaborate closely with insurance carriers and law enforcement agencies to combat organized insurance crime, operating under strict state regulatory frameworks.
An SIU investigator's operational role differs fundamentally from that of a standard desk adjuster. They conduct intensive background inquiries, perform detailed interviews, execute field inspections, and coordinate with specialized forensic experts. Importantly, referral to an SIU does not mean a fraud finding is predetermined or inevitable. Many investigations successfully conclude by determining that the initial anomaly resulted from an administrative error, a misunderstanding, or an easily resolvable documentation gap.
One of the most effective ways for a policyholder to prevent unnecessary investigative friction is to provide accurate, consistent documentation from the very beginning of the claims process. This does not require generating an overwhelming volume of paperwork; rather, it requires ensuring that every piece of information supplied faithfully reflects verifiable facts.
Dates, physical locations, damage descriptions, repair invoices, and financial figures should be as precise as possible. If specific details are uncertain—such as the exact purchase date of a damaged household item—it is always safer to label the figure as an educated estimate rather than present an unverified guess as absolute fact. Maintaining original digital files, time-stamped photographs, and organized electronic communication logs provides a chronological backbone that makes verifying a loss straightforward, ensuring that honest policyholders can navigate routine anti-fraud verification systems with absolute confidence.