
Insurance is often purchased with a straightforward expectation: when a serious loss occurs, the policy will provide financial protection. However, the actual value of an insurance policy depends on more than the type of coverage listed on a declaration page. Policy language, exclusions, limits, claim procedures, and the information exchanged during the insurance process all influence how protection works in practice.
This creates a unique challenge for consumers. Insurance companies evaluate risks, develop policy contracts, and handle claims as part of their everyday operations, while many policyholders only examine their insurance documents when a problem occurs. Consumer protection rules exist to help reduce this information gap by encouraging transparency, fair procedures, and accountability.
In the United States, insurance regulation is primarily handled at the state level. State insurance departments and regulators oversee areas such as insurer licensing, consumer complaints, and market conduct. Although specific requirements vary among states, the general purpose is to support a balanced insurance system where consumers understand their rights and insurers follow established standards.
Consumer protection does not guarantee that every claim will be approved or that every dispute will be resolved in favor of a policyholder. Instead, it establishes expectations for how insurance information is provided, how claims are reviewed, and how disagreements are handled.
Insurance contracts are different from many common purchases because the value of the product often becomes clear only after a future event occurs. A person may pay premiums for years before filing a claim, and the most important parts of the policy may not receive attention until a loss happens.
A homeowner may believe that property insurance protects against major damage to the home, for example, but the outcome of a claim can depend on the cause of the damage, exclusions in the contract, coverage limits, and whether policy conditions were satisfied.
A common misunderstanding is that having an insurance policy means every type of related loss is covered. In reality, insurance policies are designed around specific risks. A policy may provide broad protection in one area while excluding certain events, circumstances, or types of damage.
Consider a small retail business that purchases general liability insurance. The owner may understand the policy as protection against customer injuries or property damage claims. Several years later, the business begins offering installation services and signs larger commercial contracts. The owner may assume the existing policy automatically extends to these new activities.
However, the insurer may evaluate the expanded operations differently because the risk profile has changed. The new services may involve different exposures, higher contract obligations, or additional safety considerations. The issue is not necessarily that the original policy was inadequate; rather, the business circumstances changed and the coverage may need to be reviewed.
Consumer protection helps address these situations by encouraging clearer communication about what a policy covers, what limitations exist, and what responsibilities apply to both parties.
Insurance regulators play an important role in maintaining standards within insurance markets. Their responsibilities generally include monitoring insurer practices, reviewing complaints, and overseeing whether companies comply with applicable insurance regulations.
Consumers can usually find complaint information through their state insurance department or insurance regulator. These resources provide a way for policyholders to raise concerns when they believe there may be issues involving claim handling, communication, or other insurer practices.
Regulatory oversight is not limited to individual disputes. Regulators may examine patterns involving repeated complaints to determine whether a broader issue exists.
For example, suppose an insurance regulator notices a significant increase in complaints involving delayed claim responses from a particular insurer. The regulator may review the insurer’s procedures, communication practices, and claim handling processes to determine whether the problem reflects a larger market conduct concern.
This type of review does not mean every delayed claim represents improper conduct. Claims can involve complex investigations, missing information, or disagreements about coverage. The purpose of regulatory oversight is to determine whether insurers are following fair and consistent procedures.
Insurance consumer protection begins before a claim is filed. Clear information at the time of purchase helps consumers understand what they are buying and how coverage may apply in different situations.
Insurance policies contain many details that influence future decisions. A general description of coverage may explain the purpose of a policy, but the complete contract determines the actual protection available.
Important policy information usually includes:
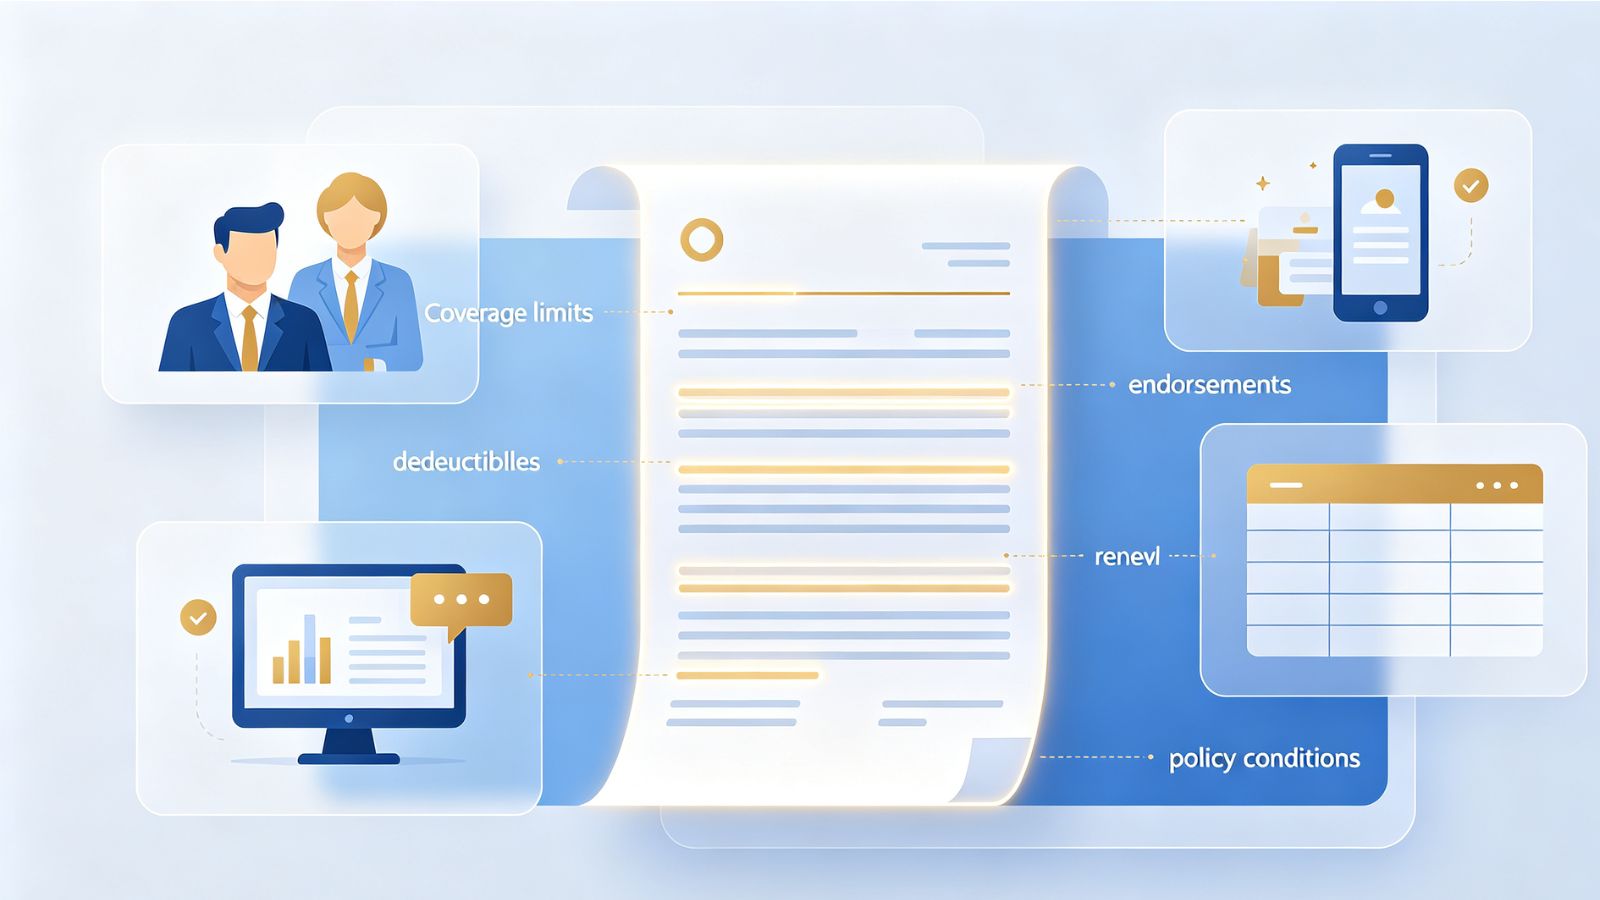
Coverage limits: The maximum amount available for certain covered losses.
Deductibles: The amount a policyholder may need to pay before insurance coverage applies.
Exclusions: Specific risks or situations that are not covered under the policy.
Endorsements: Changes or additions that modify the original policy terms.
Policy conditions: Requirements that may affect how coverage applies, including reporting procedures or documentation responsibilities.
These details matter because insurance protection depends on the entire contract rather than a general understanding of what the insurance is intended to accomplish.
Another area where misunderstandings occur is policy renewal. A consumer may assume that a renewed policy provides exactly the same protection as the previous year’s version. However, policy terms, limits, endorsements, or pricing may change during renewal. Reviewing updated documents helps identify differences before they become relevant during a claim.
Most insurance disagreements develop because two parties interpret the same situation differently. A policyholder may focus on the purpose of purchasing insurance, while the insurer must evaluate the claim according to contract language and available evidence.
An automobile claim provides a common example. After a collision, a vehicle owner may believe certain repairs are necessary to restore the vehicle. The insurer may reach a different assessment based on damage evaluations, repair estimates, or policy terms. Resolving the disagreement requires reviewing information rather than relying only on assumptions about what insurance should cover.
Commercial insurance disputes can involve even more complex questions. A construction company, for example, may believe its general liability policy applies after a claim involving a subcontractor. The insurer may examine the contract terms, the nature of the work performed, and whether additional coverage requirements applied.
In these situations, clear explanations are important. A policyholder benefits from understanding whether a disagreement involves coverage exclusions, insufficient documentation, claim valuation, or another issue.
Documentation often plays a major role. Photos, receipts, contracts, inspection reports, repair estimates, and written communications can help establish the facts of a claim and provide a clearer basis for discussion.
The claims process is where insurance protection becomes a practical service. A policy may appear simple when purchased, but its real value is tested when a consumer experiences a loss.
Fair claims practices establish expectations for how insurers investigate and communicate about claims. Although specific requirements vary by state, these standards generally focus on areas such as reasonable investigation, timely communication, accurate explanations, and proper handling of claim information.
A fair claims process does not mean every reported loss will result in payment. Insurance companies must apply the terms of the contract and determine whether the circumstances fall within the coverage provided.
At the same time, consumers benefit when claim decisions are explained clearly. A denial or limitation without an understandable reason can create confusion, while a detailed explanation allows policyholders to review how the policy language was applied.
Fair claim handling also depends on cooperation between both sides. Insurers need accurate information to evaluate losses, while policyholders benefit from maintaining records and responding to reasonable requests during the review process.
Accountability also extends beyond individual claims. Regulators may review complaint patterns and market conduct concerns to determine whether an insurer’s practices create broader issues within the insurance market.
Consumer protection works best when regulations and informed decisions operate together. Rules can create standards for fair treatment, but understanding insurance information helps policyholders maintain coverage that reflects their actual circumstances.
Insurance needs change over time. A family may acquire additional assets, a homeowner may complete major improvements, or a business may expand into new areas. These changes can affect whether existing coverage remains appropriate.
Keeping organized records is another practical part of managing insurance. Maintaining copies of policies, endorsements, renewal documents, and claim communications can make future discussions easier when questions arise.
Consumers do not need to become insurance specialists to make better decisions. A basic understanding of policy terms, coverage limitations, and claim procedures can help prevent misunderstandings and encourage more effective communication with insurers.
Consumer protection in insurance markets is built around transparency, fair procedures, and accountability. Insurance contracts will always contain technical language because they must address many different types of risks, but consumers benefit when important information is communicated clearly and decisions are explained properly.
Disclosure requirements help policyholders understand coverage before problems occur, while fair claims practices provide structure when losses happen. Regulatory oversight adds another layer by helping identify broader problems that may affect consumers beyond a single claim.
Understanding these protections does not remove every insurance disagreement, but it gives consumers a clearer framework for evaluating coverage, communicating with insurers, and making informed decisions.
Insurance laws and consumer protections vary by state, and individual outcomes depend on the specific policy language, facts of the situation, and applicable regulations. This article provides general information about insurance consumer protection and does not replace advice from a licensed insurance professional, state insurance regulator, or legal advisor who can evaluate a specific situation.