
Stepping across international borders instantly changes far more than just your local time zone. Once a traveler departs the United States, foreign medical care facilities, local legal frameworks, currency payment networks, and consumer protection statutes frequently operate under entirely unfamiliar rules. Routine disruptions that are easily resolved on domestic soil can quickly escalate into complex crises when language barriers, institutional differences, or limited access to American consular services complicate the situation.
For U.S. travelers, effective cross-border risk management is rarely about attempting to anticipate every conceivable worst-case scenario. Instead, it relies on preparing adequately for situations where the operational consequences of a mishap become disproportionately expensive or legally difficult to resolve. Medical emergencies, foreign legal entanglements, compromised financial liquidity, and sudden travel interruptions each demand a distinct, tailored response strategy. Addressing these potential vulnerabilities prior to departure dramatically reduces the number of high-pressure decisions that must be made while stranded abroad.
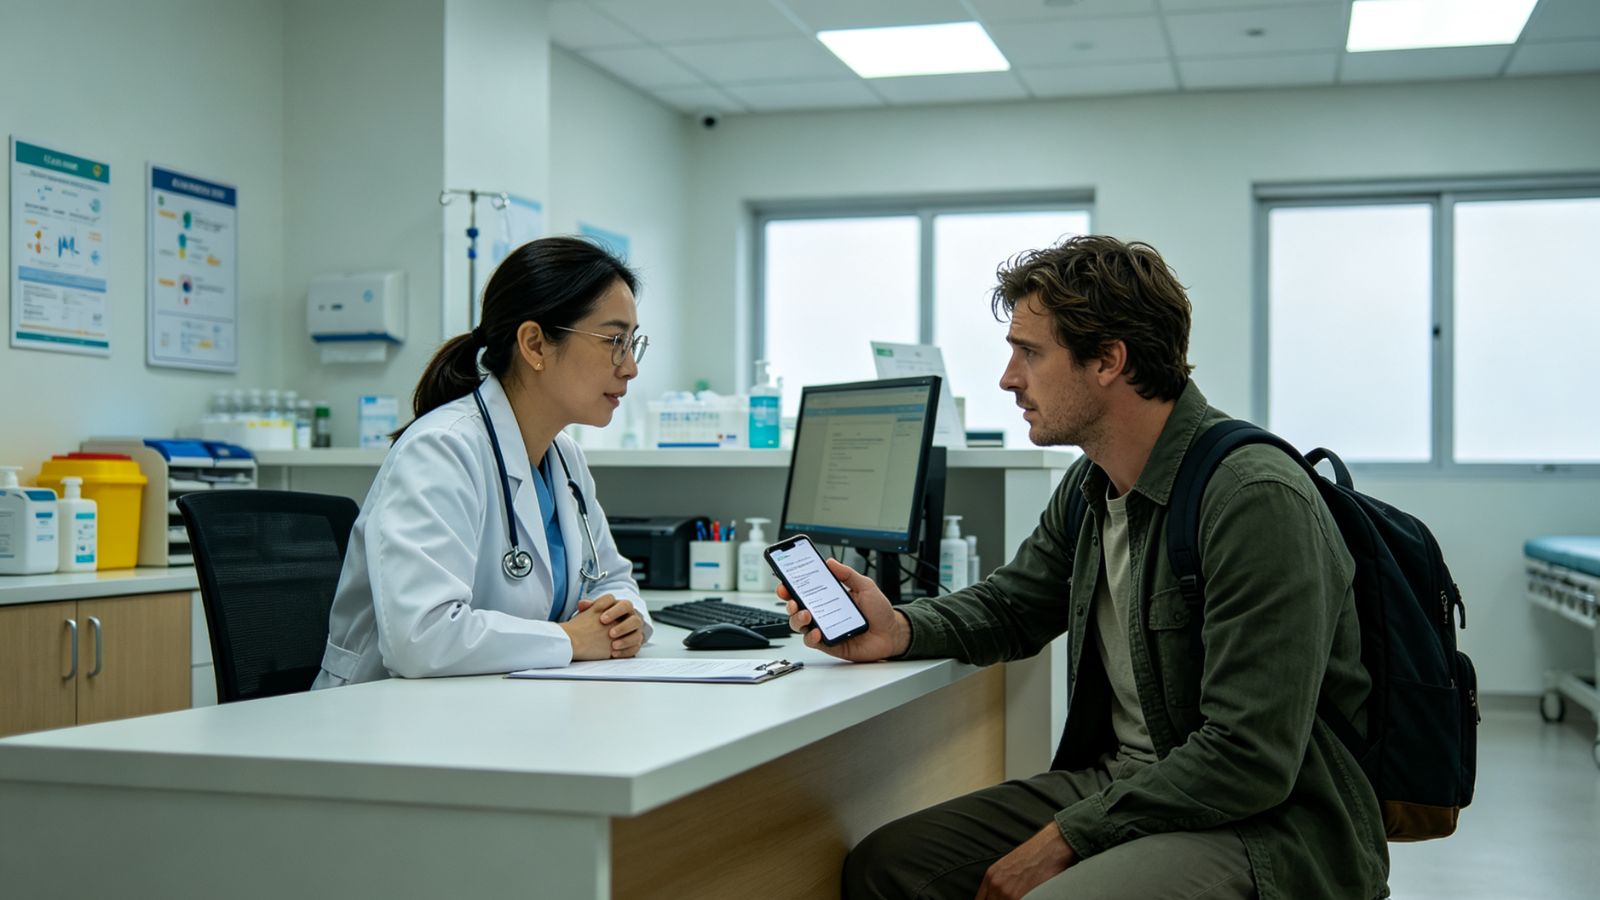
A pervasive and dangerous assumption among international travelers is that domestic health insurance policies automatically follow them overseas. In reality, standard domestic medical coverage varies wildly across international borders, and foreign healthcare providers frequently demand immediate out-of-pocket cash payment or credit card guarantees before rendering non-emergency services, leaving reimbursement battles for later. Official guidance from the Centers for Disease Control and Prevention consistently advises verifying existing policy terms well before departure and purchasing dedicated travel health or medical evacuation insurance when domestic coverage proves inadequate.
Furthermore, medical evacuation represents an entirely separate financial and logistical exposure from ordinary hospital treatment. While a local clinic may stabilize a traumatic injury or acute illness, transporting a patient via air ambulance to a facility equipped for specialized care can easily cost tens or hundreds of thousands of dollars. Public health advisories note that international medical evacuations from remote regions can surpass a quarter of a million dollars, a cost that standard health insurance rarely absorbs.
Travelers must thoroughly review their policy terms to identify preauthorization requirements, understand strict exclusions regarding preexisting conditions or high-risk adventure activities, and carry secure digital copies of essential medical records and emergency contact details.
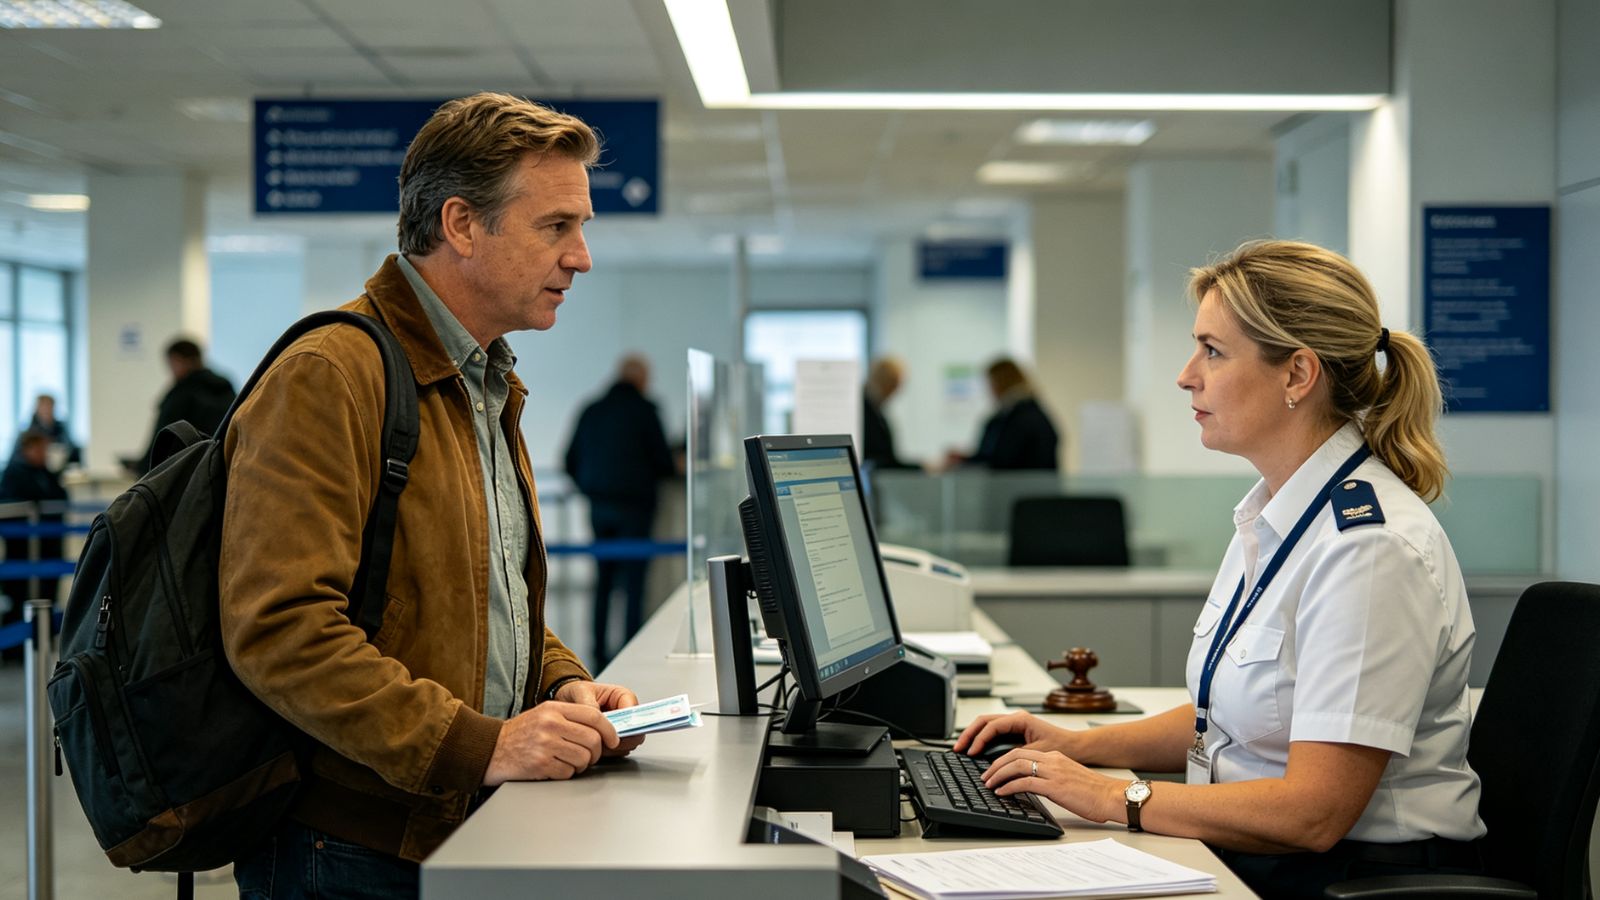
Navigating legal risk abroad is fundamentally different from managing medical or financial friction because foreign visitors remain unconditionally subject to the statutory laws of the host country. Conduct that is considered legally insignificant or entirely routine under American law may be heavily criminalized or strictly regulated elsewhere. Local statutes concerning prescription narcotics, public photography, vehicle operation, mandatory identification carriage, and commercial transactions vary drastically between foreign jurisdictions.
Crucially, the U.S. government possesses no legal authority to impose American constitutional standards upon a foreign judicial proceeding. U.S. Department of State protocols explicitly warn that citizens detained or arrested overseas are subject to local law enforcement systems, and consular officials cannot secure immediate release or act as defense attorneys. While consular personnel can help compile lists of local legal counsel or notify distressed families back home, they cannot override sovereign legal systems. Travelers should never assume that a U.S. lawyer can directly manage a foreign court proceeding or that an American legal precedent will govern an overseas dispute.
A traveler can possess substantial overall wealth and still experience a severe financial emergency if immediate access to liquid funds is severed. A lost wallet, a frozen payment card due to suspicious foreign activity alerts, a compromised smartphone, or an unexpected hospital deposit requirement can paralyze a trip even when the underlying bank account remains fully funded.
A sensible, proactive approach relies on eliminating single points of failure across payment methods. Travelers should carry multiple credit and debit cards issued by different banking institutions, keeping them stored separately from primary identification documents. It is equally vital to notify card issuers of foreign travel itineraries in advance to prevent automated fraud detection algorithms from blocking legitimate overseas purchases. While carrying a modest amount of local currency is essential for minor cash-only transactions, hoarding massive amounts of physical cash introduces unacceptable theft and loss risks. The ultimate objective is simple redundancy: losing a single payment instrument should remain a minor travel inconvenience rather than a total operational shutdown.
The broad industry label of travel insurance encompasses widely disparate forms of financial protection. Trip cancellation coverage, emergency medical insurance, and medical evacuation endorsements address entirely separate vulnerabilities, and purchasing a policy covering one category provides zero assurance regarding the others. Federal health advisories warn consumers to inspect fine-print policy exclusions rather than assuming a generic travel package covers every conceivable disaster.
The policy details become critically important when participating in specialized travel itineraries. Adventure sports, extreme recreation, and motorized excursions are routinely excluded from standard baseline policies. Moreover, reimbursement models often require the policyholder to pay massive medical bills upfront and file paperwork for repayment months later. Deductibles, geographic restrictions, and mandatory emergency assistance notification clauses dictate whether an insurance policy becomes an operational lifeline or an administrative dead end during an actual crisis.
The most valuable preparation for international travel is organizing essential information so it remains instantly accessible when you are stressed, injured, or separated from your primary luggage. Maintaining secure cloud backups of passport identification pages, visa stamps, insurance policies, prescription lists, and consular contacts ensures you are never crippled by a lost physical wallet.
Enrolling in the U.S. Department of State's Smart Traveler Enrollment Program allows embassies to push vital security updates and locate citizens during regional emergencies. Ultimately, cross-border risk management operates as a multi-layered defensive system where medical insurance, financial redundancy, and legal awareness reinforce one another. By addressing these foundational exposures before departure, travelers can explore the globe with absolute confidence.