
The traditional insurance claims workflow has historically relied upon a linear chain of manual human interactions: a policyholder reports a loss, a field adjuster gathers paper documentation, files are manually reviewed, physical damage is assessed, and a financial payout decision is eventually rendered. Today, modern digital claims infrastructure is fundamentally reshaping how each of these sequential steps is executed. Mobile applications, automated administrative workflows, artificial intelligence, connected Internet of Things devices, and secure cloud-based repositories allow critical data to flow through an active claim file with significantly reduced manual handling.
This digital transformation extends far beyond simply replacing paper forms with digital PDFs on a website. Modern technological systems are engineered to capture photographic evidence directly at the point of loss, automatically extract structured data from unstructured invoices, intelligent route claims based on complex operational characteristics, and assist claims professionals in identifying cases requiring deeper scrutiny. Guidance from the National Association of Insurance Commissioners highlights artificial intelligence, big data analytics, mobile tools, and automated workflows as core technological forces increasingly influencing how insurers process claims and interact with consumers.
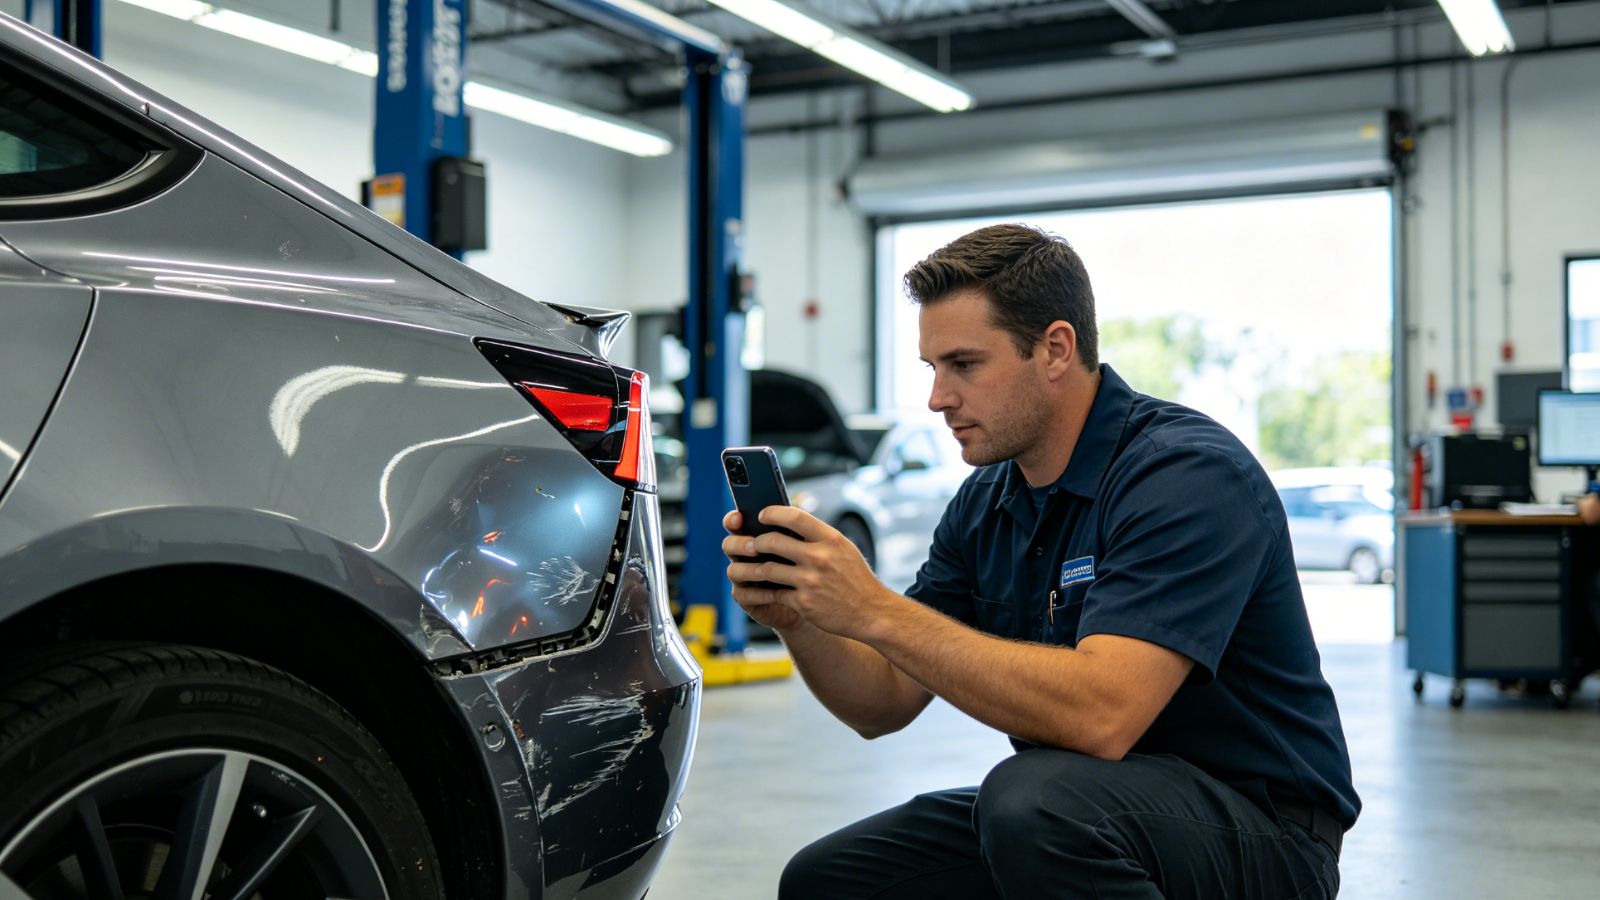
One of the most visible changes in modern claims operations is the ability to document and report a loss instantly using a personal smartphone. Instead of waiting to return to a desktop computer or mailing physical photographs, a policyholder can now submit high-resolution images, detailed text descriptions, precise GPS location data, and electronic receipts through an insurance mobile application.
For routine property or auto claims, these digital captures provide an immediate initial view of the damage long before an adjuster physically visits the site. Mobile workflows also guide users dynamically through mandatory information fields, drastically reducing the frequency of missing details. Advanced systems can ingest this data directly into the core enterprise claims platform without requiring an employee to re-key information manually.
The practical value of mobile technology, however, remains anchored to the quality and context of the captured evidence. A digital photograph alone does not establish the underlying cause of damage, the applicable policy coverage, or the final payable amount. Raw digital evidence must still be systematically evaluated against the policy contract, historical records, and the broader circumstances of the loss.
Automation is particularly powerful when applied to repetitive, high-volume administrative tasks. When a new claim is submitted, background software can instantly verify whether all required fields have been completed, generate task assignments, route the claim to the appropriate queue, send automated status updates, and request missing documentation.
Document-processing technology powered by optical character recognition can extract key data fields from repair estimates, invoices, medical bills, and statutory forms. Instead of forcing staff to transcribe data manually, automated pipelines capture names, dates, financial amounts, and policy numbers, transferring them seamlessly into claims management systems.
This operational shift does not mean human employees are rendered obsolete. Rather, automation reallocates human expertise to where it matters most. Routine administrative friction requires less manual intervention, allowing skilled claims professionals to concentrate on complex coverage questions, disputed liability, conflicting evidence, or catastrophic losses.
Artificial intelligence functions across distinct operational segments of claims handling rather than acting as a singular, automated decision-making oracle. According to regulatory oversight reports from the National Association of Insurance Commissioners, insurers deploy artificial intelligence across claims management and fraud detection, alongside underwriting and customer service.
One prominent application involves computer vision algorithms designed to analyze digital images of vehicle or property damage, assisting adjusters in categorizing repair needs. Other advanced analytical models parse millions of historical claims records to spot subtle fraud patterns or prioritize files for secondary review. Natural language processing tools also assist staff by summarizing lengthy communications, extracting data from unstructured correspondence, and locating relevant policy clauses within massive digital files.
The essential distinction in modern insurance operations lies between technological assistance and ultimate accountability. An AI-generated recommendation or automated damage estimate is never an automatic substitute for a verified factual determination.
As more evidentiary material becomes available within cloud ecosystems, adjusters operate from a continuously updated digital file rather than relying on static paperwork gathered during a single site inspection. Photographs, repair invoices, adjuster notes, and telemetry data are linked within a unified digital workflow.
This connectivity is vital when managing multi-party claims, such as an auto accident involving the policyholder, repair facility, independent appraiser, and lender. Centralized systems eliminate the friction of manually transferring information across siloed departments. Furthermore, virtual inspection tools enable adjusters to review real-time video streams from a policyholder's device, determining whether an in-person visit is truly necessary.
While speed and efficiency are primary benefits of digital infrastructure, operational velocity alone does not guarantee that a claim has been handled correctly. Insurance decisions carry significant financial and legal consequences, and automated systems can produce flawed outcomes if underlying data models are compromised.
Regulatory bodies emphasize the absolute necessity of robust governance, risk management, and strict compliance with state insurance laws when deploying automation. Frameworks from organizations like the National Institute of Standards and Technology emphasize system validity, reliability, security, privacy, and fairness. Insurers must maintain continuous oversight mechanisms to catch automated errors, review questionable algorithmic outputs, and intervene when digital systems encounter situations outside their operational parameters.
Ultimately, digital claims infrastructure is less about making every insurance claim completely autonomous than it is about redesigning the flow of information. When implemented responsibly, these technologies eliminate repetitive administrative drag and make claims processing remarkably responsive, while ensuring that human judgment remains at the heart of every critical insurance decision.