
Financial planning is often centered around saving, investing, and reducing tax obligations, but the final transfer of assets depends heavily on another important element: beneficiary designations and ownership structures.
Bank accounts, retirement plans, life insurance policies, and investment accounts often require individuals to name beneficiaries or establish ownership arrangements. However, these selections are frequently made when an account is first opened and may not receive attention for years.
Major life changes—including marriage, divorce, the birth of children, changes in family relationships, or the creation of a trust—can make previous designations outdated. Reviewing beneficiary choices and ownership structures periodically helps individuals keep their financial accounts consistent with their broader estate planning goals.
Many people assume that a will controls the distribution of all assets after death. However, not every asset passes through the probate process.
Assets with legally recognized beneficiary designations generally transfer according to the instructions recorded with the financial institution rather than the instructions written in a will. Common examples include:
Retirement accounts such as traditional IRAs, Roth IRAs, and employer-sponsored 401(k) plans.
Life insurance policies with named beneficiaries.
Payable-on-death (POD) bank accounts.
Transfer-on-death (TOD) investment accounts.
Because these assets follow their account-specific beneficiary instructions, an outdated designation can create unexpected outcomes. For example, an individual who divorces but does not update a retirement account beneficiary may leave the account subject to the previous designation rules, depending on applicable state laws and account agreements.
For this reason, beneficiary information should be reviewed whenever major personal or financial changes occur.
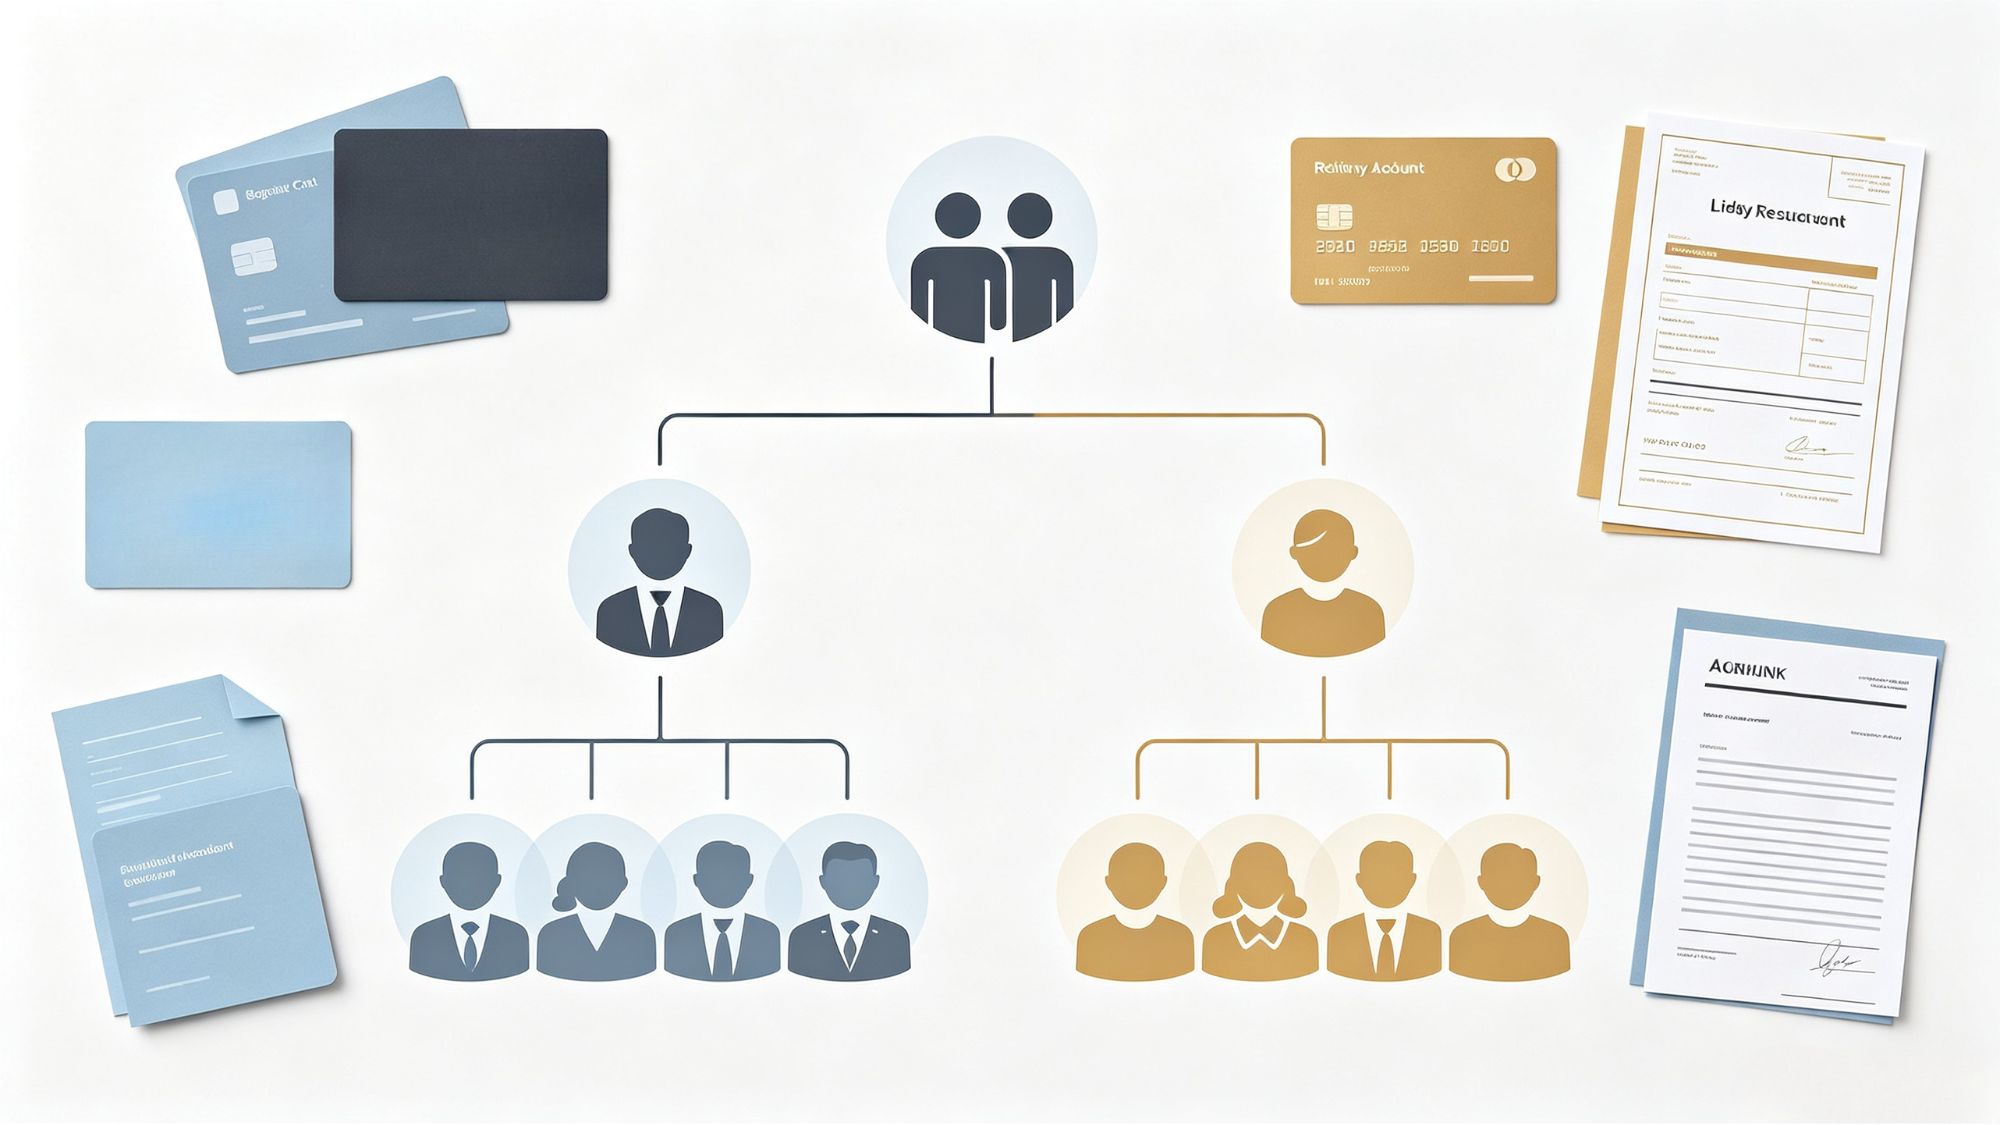
When selecting beneficiaries, financial institutions usually allow account owners to identify both primary and contingent beneficiaries.
A primary beneficiary is the first person or entity designated to receive an asset after the account owner's death.
Multiple primary beneficiaries can often be selected, with assets divided according to specified percentages. For example, an account owner may choose to divide retirement assets equally among several children or allocate different percentages based on individual circumstances.
Accurate percentage allocations and updated personal information help reduce administrative complications during the transfer process.
A contingent beneficiary acts as a backup recipient if the primary beneficiary is unable or unwilling to receive the asset.
Although some individuals focus only on naming primary beneficiaries, adding contingent beneficiaries can provide an additional layer of planning. Without a valid backup designation, certain assets may eventually become part of the estate and go through probate, depending on the account structure and applicable regulations.
Parents often want their children to receive financial assets directly, but naming minors as beneficiaries can create additional legal procedures.
Financial institutions generally cannot distribute significant assets directly to children who have not reached legal adulthood. Instead, courts may need to appoint a guardian or conservator to manage the funds until the child reaches the required age.
A common alternative is using a trust structure that provides instructions for how and when assets should be distributed. A trust may allow parents or account owners to establish conditions, such as providing funds for education, healthcare, or staged distributions at different ages.
Because trust and beneficiary decisions depend heavily on individual circumstances, many families review these arrangements with estate planning professionals.
As financial situations become more complex, some individuals use trusts to organize asset transfers and provide additional management instructions.
A revocable living trust is one commonly used structure. It allows individuals to maintain control of assets during their lifetime while creating a framework for managing or distributing assets after death.
However, creating a trust document alone does not automatically update existing financial accounts. The trust must be properly connected to specific assets through ownership changes or beneficiary designations where appropriate.
When naming a trust as a beneficiary, financial institutions typically require accurate information, including:
The legal name of the trust.
The date the trust was created.
The name of the current trustee.
Incorrect or incomplete information can delay the transfer process, making regular reviews an important part of maintaining an effective estate plan.
In some situations, individuals consider naming their estate as the beneficiary of financial accounts. While this may be appropriate in certain planning strategies, it can create additional administrative requirements.
When an estate becomes the recipient of assets, those assets may need to go through probate before distribution. Probate can involve court procedures, documentation requirements, and additional administrative steps.
For retirement accounts, beneficiary selection can also influence how distributions are handled under federal tax rules. Different beneficiary categories may receive different treatment, particularly regarding distribution timing and tax considerations.
Because these rules can be complex, beneficiary choices should be evaluated alongside an overall estate plan rather than treated as isolated account settings.
Beneficiary management is not a one-time task. Financial accounts, family circumstances, and personal goals can change over time.
A regular review process can help identify outdated information before it creates problems. Many individuals choose to review beneficiary designations annually or after major life events, including:
Marriage or divorce.
Birth or adoption of children.
Death of a beneficiary.
Creation or modification of a trust.
Opening new investment or retirement accounts.
Significant changes in financial circumstances.
During a review, individuals should confirm that:
Primary and contingent beneficiaries are still appropriate.
Names and contact information are accurate.
Newly opened accounts have updated beneficiary selections.
Ownership arrangements match current estate planning documents.
Beneficiary designations and ownership structures play a central role in determining how financial assets are transferred. While wills remain an important part of estate planning, many financial accounts follow separate beneficiary instructions that require independent management.
By understanding the difference between primary and contingent beneficiaries, considering trust structures when appropriate, and reviewing account information regularly, individuals can maintain better alignment between their financial accounts and long-term estate planning objectives.
Effective beneficiary management is not simply an administrative task—it is an ongoing process that connects everyday financial decisions with future wealth transfer planning.