
When property suffers physical damage, the final payout issued by an insurance company is rarely determined simply by whether the loss appears large or small to the naked eye. A claim may involve a repairable partial loss, a property that is economically impractical to restore, or a catastrophic total loss where the insured asset is completely destroyed. The mathematical calculation can shift dramatically depending on the policy's chosen valuation method, applicable deductibles, policy limits, depreciation schedules, and the specific class of property involved.
This fundamental distinction matters because partial losses and total losses are not merely two different percentages of property damage. They trigger entirely distinct valuation methods, legal standards, and administrative settlement procedures. Guidance from the National Association of Insurance Commissioners explains that actual cash value generally reflects replacement cost minus physical depreciation, whereas replacement cost coverage is specifically designed to pay the actual cost of repairing or replacing property with materials of like kind and quality without taking any depreciation deduction. Understanding these underlying mechanics is essential for policyholders trying to reconcile an insurer's initial estimate with the realities of rebuilding or replacing damaged assets.
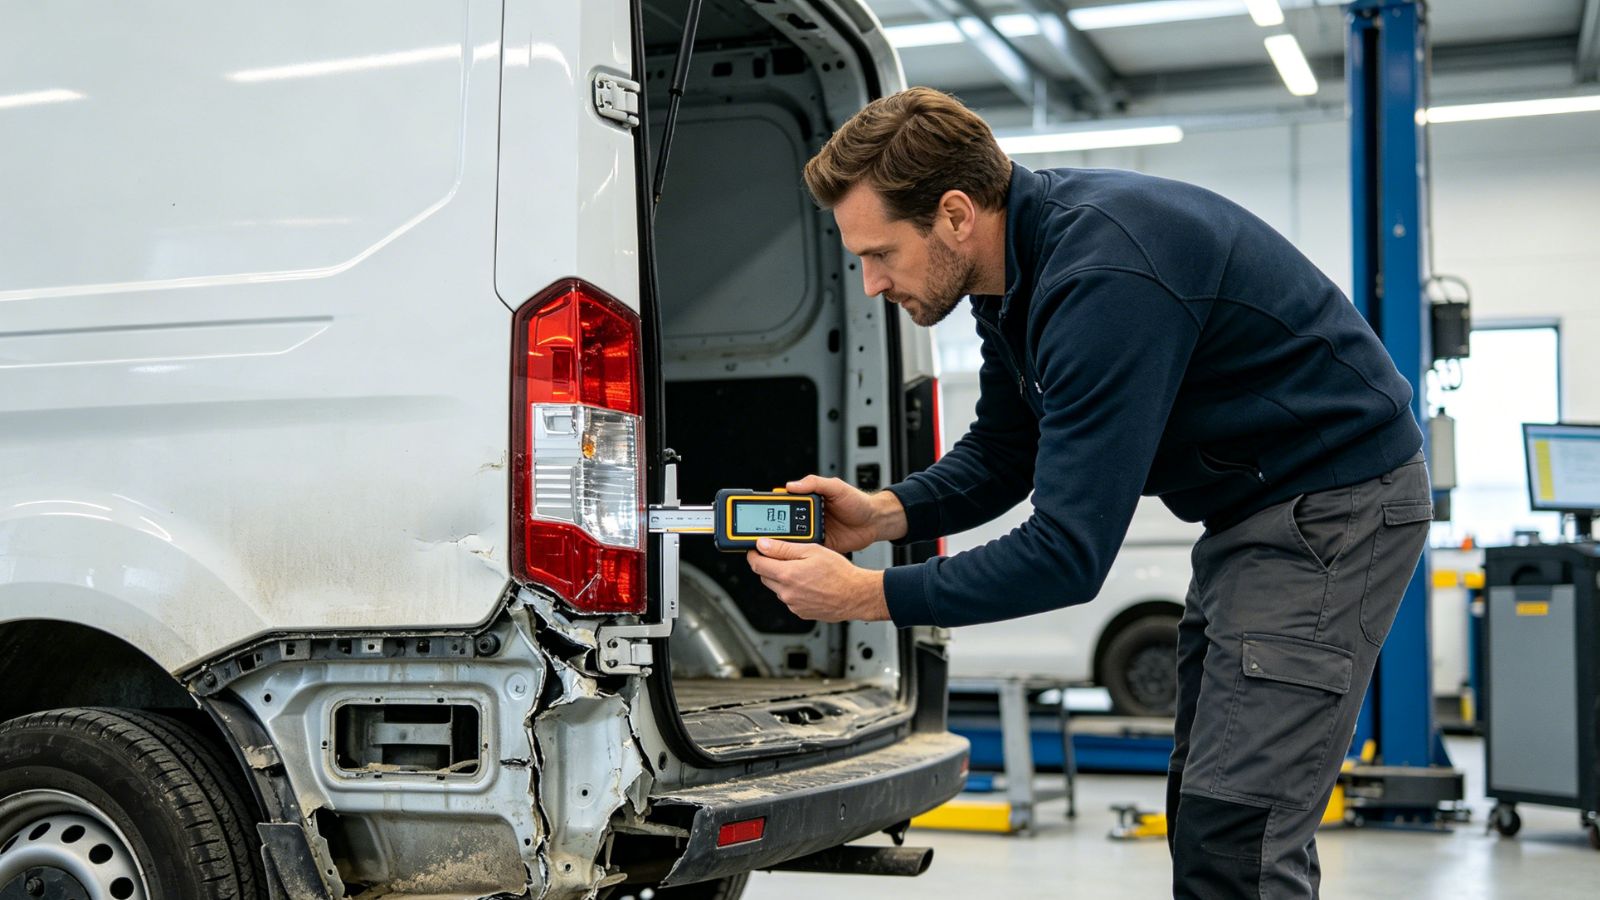
A partial loss generally means that the damaged property can be repaired, stabilized, or restored without completely replacing the entire insured structure or personal item. For instance, a severe windstorm might damage a specific section of a residential roof, a kitchen fire might ruin cabinetry while leaving the underlying framing intact, or an automobile might suffer collision damage that can be safely mended in a body shop. The settlement process therefore begins with calculating the precise cost of restoring the damaged components, subject to all governing policy limitations.
A total loss represents an entirely different financial scenario because the property is either completely destroyed or cannot reasonably be restored under applicable industry standards and state regulations. In homeowners insurance, a residence reduced to ashes by a covered fire is routinely classified as a total loss. In automobile insurance, a vehicle is typically deemed a total loss when the insurer determines that the cost of repairs exceeds a specified statutory percentage of the vehicle's pre-accident value. The Insurance Information Institute notes that auto physical-damage claims generally rely on the vehicle's actual cash value, with the insurer paying the lesser of that valuation or the actual cost to repair or replace the vehicle with one of equivalent kind and quality.
The critical takeaway is that no single nationwide formula dictates every total loss determination. The specific contract language, property type, state statutory law, and factual circumstances of each individual claim interact to shape the final outcome.
For a repairable property loss, the claims adjuster typically starts by determining what it reasonably costs to restore the compromised portion of the property. That evaluation relies heavily on professional contractor estimates, independent repair invoices, engineering assessments, and adjuster software databases.
Once the baseline restoration cost is established, the policy's valuation method becomes the defining factor. Under actual cash value coverage, physical depreciation is subtracted from the cost of repairing or replacing the damaged materials. Under replacement cost coverage, qualifying repairs are valued without any deduction for prior wear and tear, although deductibles, policy limits, sublimits, and exclusions continue to govern the final payout.
Consider a simplified homeowner scenario where covered roof repairs are estimated at eighteen thousand dollars and the policy carries a two-thousand-dollar deductible. Under replacement cost coverage, a qualifying settlement is based on the full eighteen thousand dollar repair figure minus the deductible, provided all post-loss conditions are met. Under actual cash value coverage, the insurer calculates depreciation on the old roofing materials first, subtracts that depreciation amount from the eighteen thousand dollars, and then applies the two-thousand-dollar deductible to the remainder. Because depreciation schedules and policy endorsements vary widely, actual payout figures differ substantially from case to case.
A contractor's preliminary estimate does not automatically dictate the final insurance settlement amount. The insurance company retains the contractual right to investigate what damage is genuinely covered and what work is strictly necessary to restore the property back to its pre-loss condition.
For example, an estimate provided by a contractor might incorporate modern upgrades or superior materials that were not part of the original structure. Conversely, concealed damage frequently comes to light only after demolition and repair work begin behind walls or beneath flooring. Coverage complexities also arise when specific components of a property are subjected to different valuation rules under specialized policy endorsements, such as older architectural roofs or custom artisanal finishes.
This operational reality explains why a robust claim file connects the repair estimate directly to documented physical damage rather than treating an initial estimate as absolute proof of the final settlement value.
When a piece of property is completely destroyed, there is no meaningful repair estimate to anchor the financial calculation. The central inquiry shifts from what it costs to fix an item to determining the economic value the policy provides for the property that was lost entirely.
For residential property insurance, the answer depends heavily on whether the policy relies on replacement cost, actual cash value, or another specified valuation endorsement. Replacement cost represents the amount required to rebuild or replace the structure with similar materials without deducting depreciation, whereas actual cash value factors in the age and condition of the lost property.
This distinction does not mean a homeowner automatically receives the real estate market value of the property. Replacement cost focuses strictly on the cost of physical construction, while market value includes external economic factors such as land valuation, neighborhood demand, and geographic location. Those two distinct concepts routinely generate vastly different financial figures.
Furthermore, a total loss does not automatically trigger payment of the maximum policy limit in every circumstance. Policy limits establish hard financial ceilings, but the actual payout depends on coverage grants, applicable deductibles, valuation provisions, and state laws.
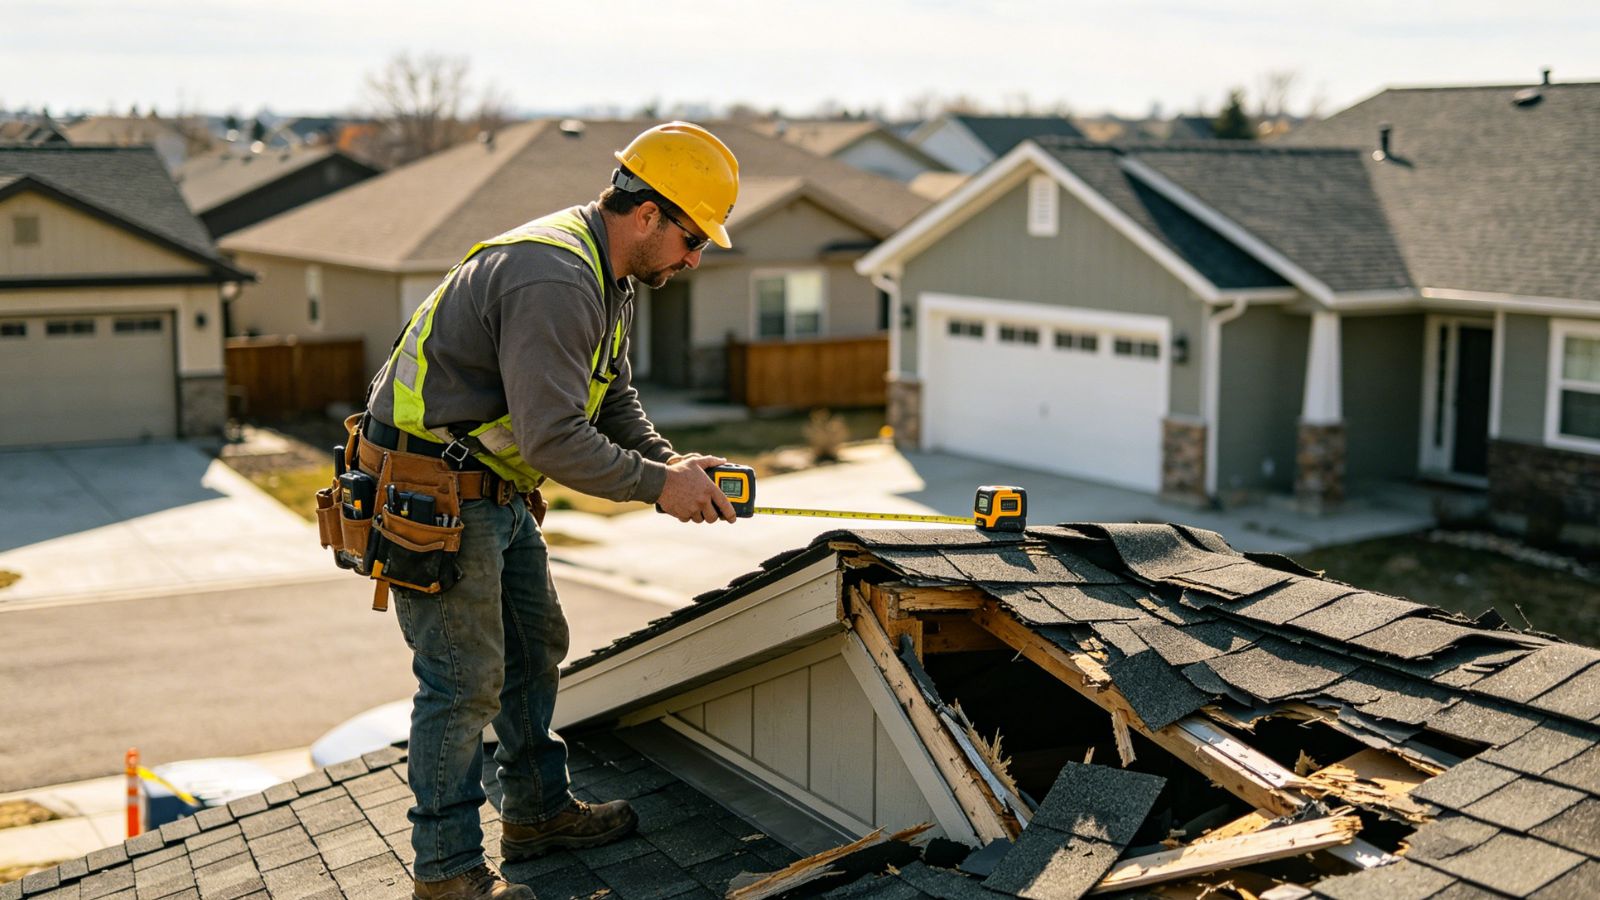
Motor vehicle claims illustrate why loss calculations cannot be generalized across different insurance categories. When physical damage occurs to an automobile, insurers evaluate actual cash value rather than the cost of constructing a brand-new vehicle from scratch.
The Insurance Information Institute notes that auto physical-damage coverage typically pays the lesser of the vehicle's actual cash value or the cost to repair or replace it with a comparable model of like kind and quality. In a total loss scenario, the actual cash value is adjusted to reflect prior mileage, overall physical condition, and wear and tear.
Consequently, two vehicles of the exact same make, model, and year can yield completely different valuations if their mileage, maintenance history, or interior condition diverge. A total loss automobile valuation is never based on what the owner originally paid at the dealership years prior. Comparing an insurer's valuation report against verified regional market data is therefore far more productive than arguing over original purchase prices.
The raw loss valuation represents only one component of the final settlement equation. A deductible establishes the fixed dollar amount or percentage of loss that the policyholder must absorb before the insurance carrier's financial obligations begin.
Policy limits create another boundary. Even if the actual cost of restoring a severely damaged property exceeds the available coverage limit, the insurer is generally not responsible for amounts beyond that cap simply because the financial loss is exceptionally large.
Depreciation is particularly vital when actual cash value provisions govern the claim. Actual cash value is defined as the repayment value for damaged property, calculated generally as replacement cost minus depreciation. Replacement cost policies handle this differently by often paying actual cash value initially, and releasing the withheld depreciation funds only after the policyholder completes and documents the actual repair or replacement work.
Whether a claim involves a minor partial loss or a catastrophic total loss, the insurance carrier requires objective evidence to establish what was lost and how the financial figures were calculated. For partial losses, photographs, repair invoices, measurements, and records of damaged components help substantiate the necessary scope of work.
For total loss claims, documentation focuses on proving ownership, detailing property characteristics, establishing pre-loss condition, and compiling valuation evidence. Maintaining a detailed home inventory is exceptionally valuable when numerous personal belongings are destroyed simultaneously in a major disaster.
The most effective documentation is not an overwhelming stack of unorganized papers, but rather a curated collection of records that clearly connects the property, its condition, the covered peril, and the claimed amount.
The distinction between partial loss and total loss is a vital analytical tool, but it should never be treated as a simplistic formula for predicting a payout. A partial loss and a total loss of identical financial magnitude can be evaluated in entirely different ways depending on the nature of the property, the governing valuation clauses, and the feasibility of repairs.
For policyholders, the most reliable starting point is always the insurance contract itself. Reviewing provisions governing loss settlement, valuation methods, deductibles, and exclusions helps clarify why two estimates differ and when a settlement calculation warrants closer professional review. Ultimately, compensation is determined by the interaction between verified evidence and the explicit terms of the insurance policy.