
A homeowner in Florida, a driver in California, and a small business owner in Texas may all purchase coverage from the same national insurance company, yet their insurance experience can be very different. The policies available to them, the prices they pay, and the protections they receive may depend heavily on the state where they live. This difference comes from one of the defining features of the U.S. insurance system: insurance is primarily regulated at the state level rather than through a single federal insurance authority.
Although many insurers operate nationwide, they must comply with the laws and regulatory requirements of each state where they sell policies. The state-based model has shaped American insurance markets for decades. Supporters argue that local regulators are better positioned to understand regional risks, while critics point to the complexity created by having many different regulatory systems. Understanding this structure helps explain why insurance rules, costs, and consumer protections can vary so significantly across state lines.
Insurance often appears to be a national industry because large companies advertise and operate across the country. From a regulatory perspective, however, the United States has a collection of connected state insurance markets rather than one single national marketplace.
Each state, the District of Columbia, and U.S. territories maintain insurance regulatory authorities. These agencies are responsible for licensing insurers and insurance professionals, reviewing certain insurance products, monitoring company practices, and enforcing state insurance laws. According to the National Association of Insurance Commissioners (NAIC), state insurance departments remain the primary regulators of insurance markets in the United States.
The modern foundation of this system is closely tied to the historical development of state authority over insurance regulation. In 1944, the U.S. Supreme Court’s decision in United States v. South-Eastern Underwriters Associationraised questions about whether insurance transactions could be subject to federal regulation under the Commerce Clause. Congress responded with the McCarran-Ferguson Act of 1945, which confirmed that states generally retain authority over insurance regulation unless federal law specifically provides otherwise.
For insurers, this means that entering a new state market requires more than simply offering the same product nationwide. Companies may need to adjust policy language, pricing practices, claims procedures, and reporting requirements to comply with local rules. For consumers, the effect is that insurance is partly shaped by geography: the state where a person lives can influence what coverage is available, how rates are reviewed, and what complaint procedures apply.
Insurance exists to manage risk, but risks are not evenly distributed across the United States. A regulatory approach that works in one region may not fully address the challenges faced in another. State regulators must consider local conditions when overseeing insurance markets, from natural disaster exposure to differences in legal requirements and consumer needs.
Florida’s property insurance market demonstrates the difficult balance between affordability and financial stability. Repeated hurricane losses have placed significant pressure on insurers, regulators, and homeowners. When claims costs rise sharply, insurers may seek higher premiums, reduce their exposure, or reconsider whether they can continue operating in certain areas.
Regulators must weigh competing priorities. Consumers need access to reasonably priced coverage, but insurers must collect enough premium revenue to pay claims after major disasters. Florida’s experience shows why insurance regulation is not simply about controlling prices; regulators must also consider whether the market remains capable of supporting future claims.
The state’s experience also illustrates the role of residual market mechanisms. When private insurers reduce participation in high-risk areas, state-created programs may provide an alternative source of coverage for eligible policyholders. These programs can help maintain availability, but they also raise questions about how much risk should be carried by public systems rather than private insurers.
California provides another example of how local conditions influence insurance regulation. Increasing wildfire risk has affected how insurers evaluate property exposure, manage risk, and determine where they will continue writing policies. Regulators face the challenge of maintaining consumer access to coverage while recognizing the changing cost of natural disasters.
The broader issue is not limited to one state. As climate-related risks increase in different regions, regulators across the country are examining how insurance markets can remain available and financially sustainable. These discussions highlight a central challenge of insurance oversight: prices must reflect risk, but coverage must also remain accessible to consumers.
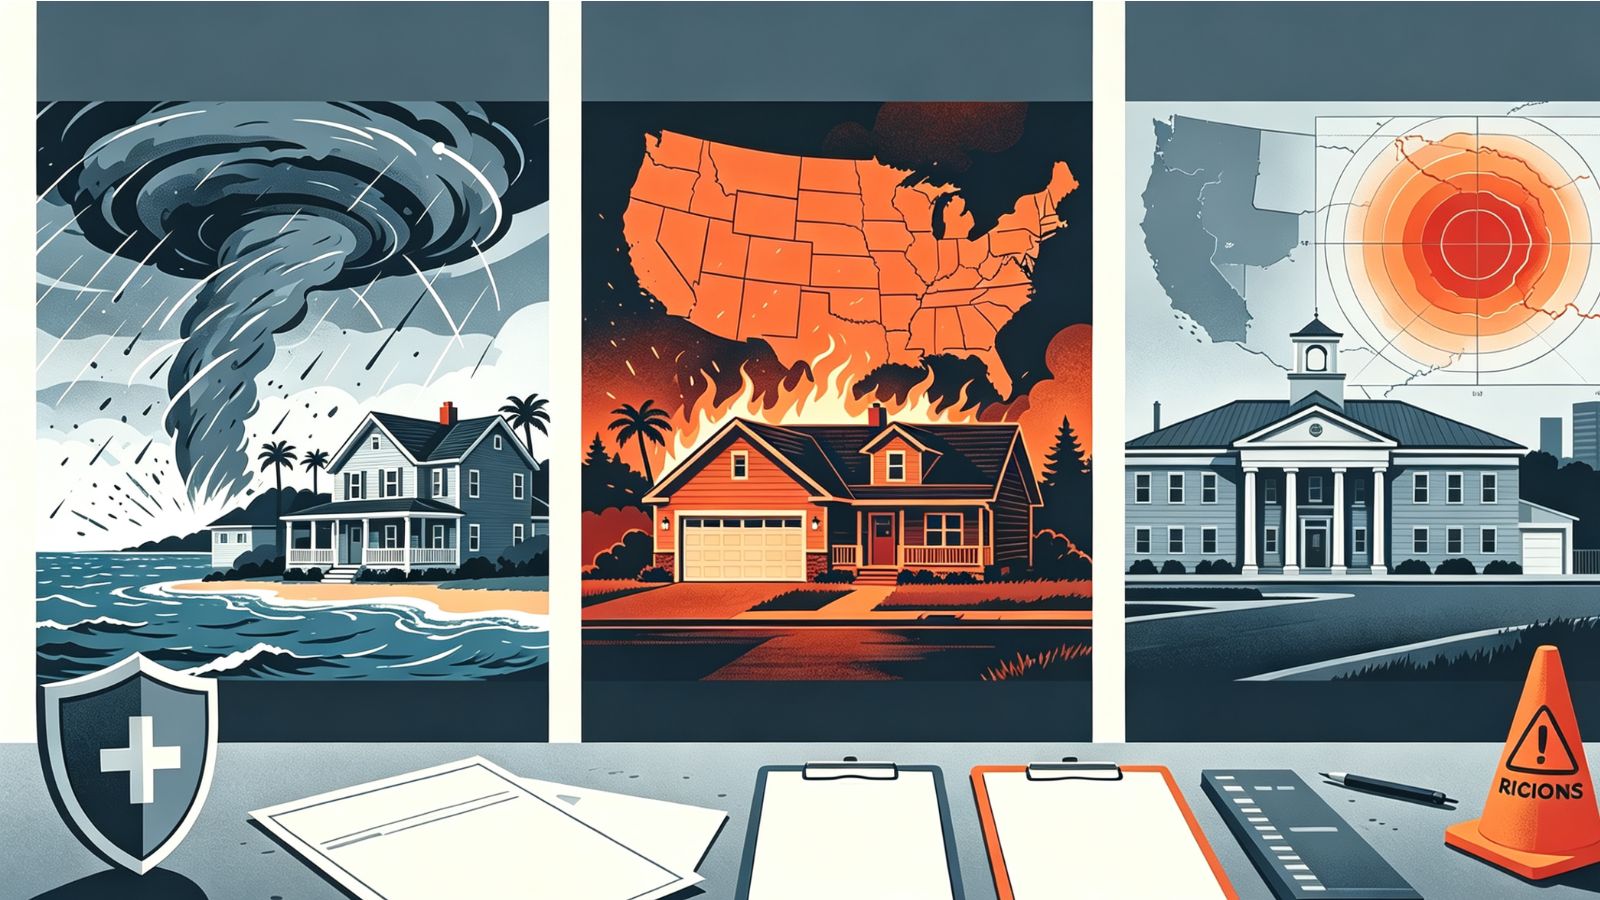
Insurance oversight does not begin when something goes wrong. State regulators influence insurance products before they reach consumers and continue monitoring companies after policies are sold.
Insurance policies are detailed legal contracts. They define covered events, exclusions, deductibles, claim procedures, and limitations. Many states review insurance policy forms to ensure that contracts comply with state law and do not contain unfair or misleading provisions.
This process helps create minimum standards for clarity and consumer protection. A small difference in policy wording can affect whether a claim is covered, which is why regulatory review of contract language remains an important part of insurance oversight.
Insurance pricing is another major area of state supervision. States use different approaches to reviewing insurance rates. Some require insurers to obtain approval before certain rate changes take effect, while others use systems that allow insurers to adjust rates while remaining subject to regulatory review.
The purpose of rate regulation is not simply to prevent higher premiums. Regulators must also consider whether insurers have enough financial resources to pay future claims and remain stable during periods of significant losses.
State oversight continues throughout the life of an insurance policy. Insurance departments monitor areas such as:
Claims handling practices
Advertising and sales activities
Consumer complaints
Compliance with insurance laws
Market conduct standards
Market conduct examinations allow regulators to evaluate whether insurers are treating customers fairly. These reviews may identify issues involving claim delays, improper communications, or patterns of unfair business practices.
However, regulation does not guarantee that every claim will be approved. Insurance policies remain contracts, and claim decisions depend on the specific terms of the policy and the circumstances surrounding a loss.
One of the most important responsibilities of insurance regulators happens behind the scenes: making sure insurers remain financially capable of paying claims.
Insurance companies collect premiums today in exchange for promises to pay future losses. If an insurer does not maintain adequate financial resources, policyholders may face serious problems when they need coverage most.
State regulators monitor insurer financial health through tools such as:
Financial examinations
Reserve analysis
Capital evaluations
Risk-based capital frameworks
Risk-based capital standards help regulators evaluate whether an insurer has enough capital relative to the risks it takes. These standards are designed to identify companies that may face financial stress before problems become severe.
If a company becomes financially troubled, regulators can intervene through supervision, rehabilitation efforts, or liquidation procedures designed to protect policyholders. This part of insurance regulation receives less public attention because consumers usually notice insurance when buying a policy or filing a claim, but financial oversight is essential to maintaining confidence in the system.
The state-based insurance system has existed for generations, but it continues to generate debate.
Supporters argue that state regulators have advantages because they understand local markets, regional risks, and consumer concerns. A regulator dealing with hurricane exposure in Florida or wildfire risk in California may be better positioned to address those issues than a distant national authority.
Critics argue that the system creates unnecessary complexity. Insurers operating nationwide must comply with different rules, approval processes, and reporting requirements across many jurisdictions. They believe greater national consistency could reduce administrative costs and simplify consumer experiences.
The debate reflects a broader question in American regulation: whether local flexibility or national uniformity creates better outcomes. So far, policymakers have generally maintained a state-centered system while expanding cooperation among regulators.
A system involving dozens of regulators requires cooperation. State insurance departments coordinate through organizations such as the National Association of Insurance Commissioners (NAIC).
The NAIC does not directly regulate insurance companies. Instead, it helps state regulators develop model laws, financial reporting standards, examination practices, and regulatory resources. States may adopt NAIC model standards, but implementation can differ significantly between jurisdictions.
This structure represents a compromise between two approaches: complete federal regulation and completely independent state systems. It allows states to maintain authority while creating greater consistency in areas where cooperation is useful.
Insurance regulation provides important protections, but consumers should understand what regulation can and cannot do.
Oversight does not make every policy identical, guarantee that every claim will be paid, or eliminate all market risks. Consumers still need to understand their own coverage choices.
Practical steps include:
Reviewing coverage limits, exclusions, and deductibles before purchasing a policy
Confirming that insurers and agents are properly licensed in their state
Using state insurance department resources when researching companies or filing complaints
Comparing policies based on coverage details rather than price alone
A regulated insurance market works best when consumers understand both their rights and the limits of their coverage.
Insurance markets continue to change as new risks emerge. Climate-related losses, artificial intelligence, cybersecurity concerns, and the increasing use of consumer data are creating new regulatory questions.
State agencies are examining how traditional oversight methods can adapt to new technologies and changing risk patterns. Future debates will likely focus on how to preserve the advantages of state-level expertise while improving coordination across state lines.
For now, the U.S. insurance system remains a state-based structure supported by national cooperation.
The architecture of U.S. insurance regulation reflects a long-standing effort to balance consumer protection, market stability, and local decision-making.
State oversight allows regulators to respond to regional conditions, but it also means that insurance experiences can differ significantly from one state to another. Behind every insurance policy is not only a contract between a customer and an insurer, but also a regulatory system designed to support fairness, financial strength, and accountability.
Understanding how this system works helps consumers make better decisions and provides a clearer picture of why American insurance markets operate the way they do.