
An insurance claim officially begins the moment a policyholder reports a covered loss, but the resolution process rarely concludes with a single, immediate payment. Between those two points, an insurance carrier may investigate the sequence of events, confirm whether the specific policy contract applies, assess the physical or financial damage, review supporting documentation, and determine precisely how much is payable under the governing policy terms. While the exact procedural sequence can vary significantly depending on the type of insurance product, state-level regulatory requirements, and the unique circumstances of the loss, most claims move through several recognizable operational stages.
Understanding the insurance claims lifecycle can transform an unfamiliar and often stressful experience into a transparent, manageable process. It also clarifies why an insurer may request extensive documentation—such as photographs, repair estimates, medical records, receipts, or signed statements—before reaching a final decision. A claim is ultimately evaluated against the binding language of the insurance contract and the available evidentiary record, rather than simply matching the total dollar amount a policyholder believes they lost.
The first formal stage in the lifecycle is always the notification of loss. Following an unexpected event such as a vehicle collision, property damage incident, theft, or another potentially covered mishap, the policyholder contacts the insurer directly or utilizes its designated digital reporting system. This initial report establishes critical baseline facts: precisely when and where the event occurred, what happened, what physical or financial assets were damaged, and whether there are any immediate safety hazards requiring urgent intervention.
Prompt reporting is essential because most insurance policies contain explicit notice requirements, though the legal consequences of a delayed notice depend heavily on specific policy language and applicable state laws. Policyholders should provide accurate, objective information rather than attempting to guess uncertain details or present unconfirmed speculations as established facts. If circumstances are still actively developing, distinguishing confirmed knowledge from unknown variables protects the integrity of the claim. Once received, the insurer creates a formal claim file and assigns a unique claim number. Depending on the complexity of the loss, an adjuster or specialized claims professional is then assigned. Opening a file does not by itself establish that the loss is covered or determine how much the insurer will ultimately pay.
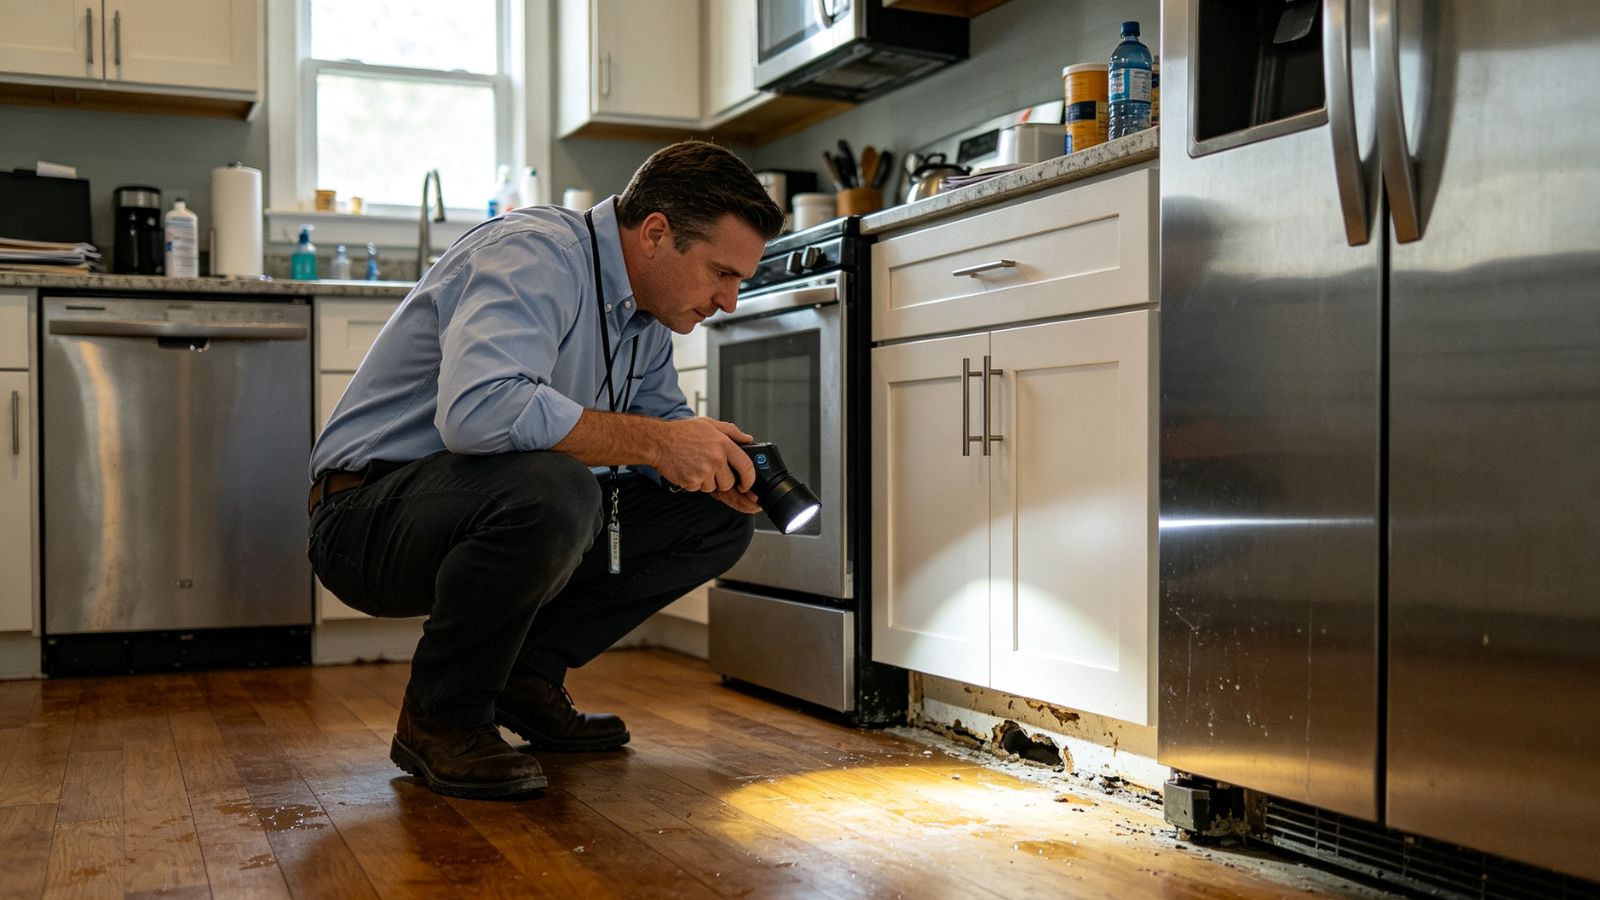
Once a claim is officially logged, the insurer launches an investigation into the surrounding circumstances. The primary purpose of this phase is not simply to calculate a monetary payout, but to establish an accurate factual timeline, identify the damaged property, determine whether the event falls squarely within policy coverage, and assess whether any exclusions, conditions, deductibles, or policy limits apply. This investigative phase can involve vastly different forms of evidence depending on the nature of the coverage.
A property damage claim typically requires physical inspections, contractor estimates, photographs, and detailed repair inventories. An auto insurance claim generally necessitates vehicle inspections, police accident reports, witness statements, and body shop assessments. This rigorous investigation explains why an insurance claim frequently takes longer than a policyholder initially anticipates. Straightforward claims with unambiguous evidence move rapidly through the pipeline, whereas incidents involving disputed facts, extensive structural damage, or complex coverage questions require thorough, time-consuming evaluation.
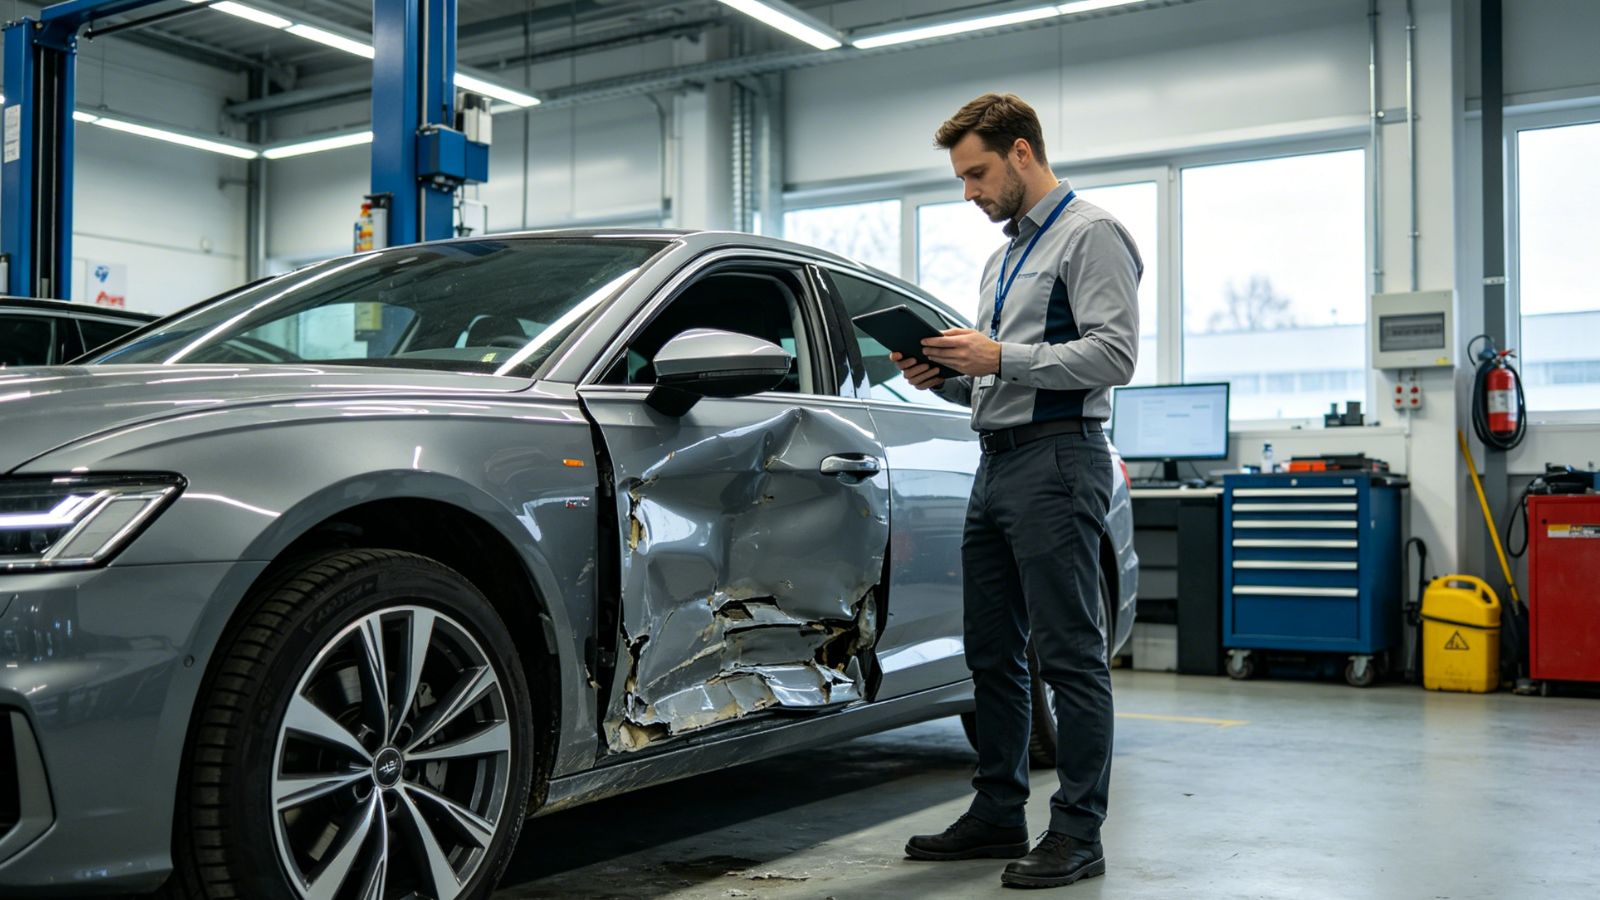
A widespread misunderstanding among policyholders is the assumption that proving physical damage automatically proves insurance coverage. In reality, these are entirely separate contractual questions. An insurance carrier can readily agree that a loss or item of damage occurred while simultaneously determining that the specific cause of loss falls outside the policy's defined coverage scope. The insurance policy itself provides the structural framework for every coverage decision.
Relevant contractual provisions include designated causes of loss, specific policy exclusions, conditions precedent, deductibles, aggregate limits, valuation rules, and attached endorsements. Because these clauses vary substantially across different insurance products and providers, the outcome of one claim cannot reliably predict the resolution of another seemingly identical situation. Understanding this distinction prevents misplaced expectations and anchors discussions in the actual text of the agreement.
After establishing the underlying facts and confirming that coverage applies, the claims process transitions directly toward valuation. The insurer must quantify the precise amount of financial loss covered under the terms of the policy. While valuation can be straightforward when dealing with standard, well-documented invoices, many claims require professional judgment and specialized appraisal techniques. Property damage requires detailed contractor estimates, while personal property claims demand proof of prior ownership, physical condition, and replacement value.
The policy's chosen valuation methodology is critically important here. Many policies maintain a strict distinction between actual cash value and replacement cost, while deductibles and maximum policy limits directly reduce the final amount payable. Consequently, a policyholder's total out-of-pocket economic loss and the insurer's final covered payout are rarely identical figures. Preserving evidence, maintaining meticulous receipts, and following insurer instructions regarding damaged property are essential steps that directly support the valuation process.
Not every claim moves smoothly from investigation straight to a single final payout. In many complex scenarios, an insurer will issue a partial or interim payment while major repairs or supplemental investigations remain ongoing. This occurs when a portion of the loss is clearly established and undisputed, allowing the policyholder to begin essential recovery work before the entire claim is fully resolved.
Disagreements regarding scope or value can also surface. A policyholder may believe that a wider area of damage should be covered, while an insurer interpreting the contract differently arrives at a lower valuation. Reviewing the written explanation provided by the insurer and comparing it directly with the policy language helps clarify the exact nature of the dispute. State insurance departments and resources provided by the National Association of Insurance Commissioners remind consumers that insurance regulation occurs primarily at the state level, meaning available consumer protections and dispute resolution remedies vary by jurisdiction.
A claim ultimately reaches its settlement phase when the insurer has completed all necessary evaluations and determined the final payable amount under the policy terms. Depending on the structure of the claim and any external financial interests, payment may be issued directly to the policyholder or distributed jointly with other interested parties, such as a mortgage lender, lienholder, or specialized service provider.
The final settlement figure must always be viewed through the lens of the policy contract rather than the initial rough estimate. Applicable deductibles, coverage caps, and non-reimbursable expenses mean a settlement does not necessarily cover every single dollar associated with an unfortunate incident. Once payments are disbursed and administrative requirements are satisfied, the active claim file is formally closed. However, if a policyholder believes a settlement decision is flawed, the underlying policy and state regulations often outline formal avenues for review, re-examination, or dispute resolution, ensuring the claims lifecycle remains a structured, accountable process from start to finish.