
When an insurance loss occurs, the quality and organization of the evidentiary record can significantly influence how efficiently a claim is investigated, processed, and evaluated. Photographs, repair estimates, receipts, medical records, billing statements, and chronological records of communication help establish what actually happened, what physical assets were damaged, what out-of-pocket expenses were incurred, and which amounts are properly claimable under the governing policy. The National Association of Insurance Commissioners (NAIC) specifically recommends documenting insurance losses comprehensively with photographs, videos, official reports, receipts, and other robust supporting records to eliminate ambiguity. However, systematic evidence collection is never about creating the largest or most overwhelming file possible; rather, it is about constructing a clear, coherent, and organized record that directly connects an unexpected incident to the resulting financial losses. Because specific evidentiary requirements vary widely by insurance product, policy language, and state jurisdiction, policyholders should always coordinate their documentation efforts alongside the actual policy contract and explicit instructions from their claims adjuster.
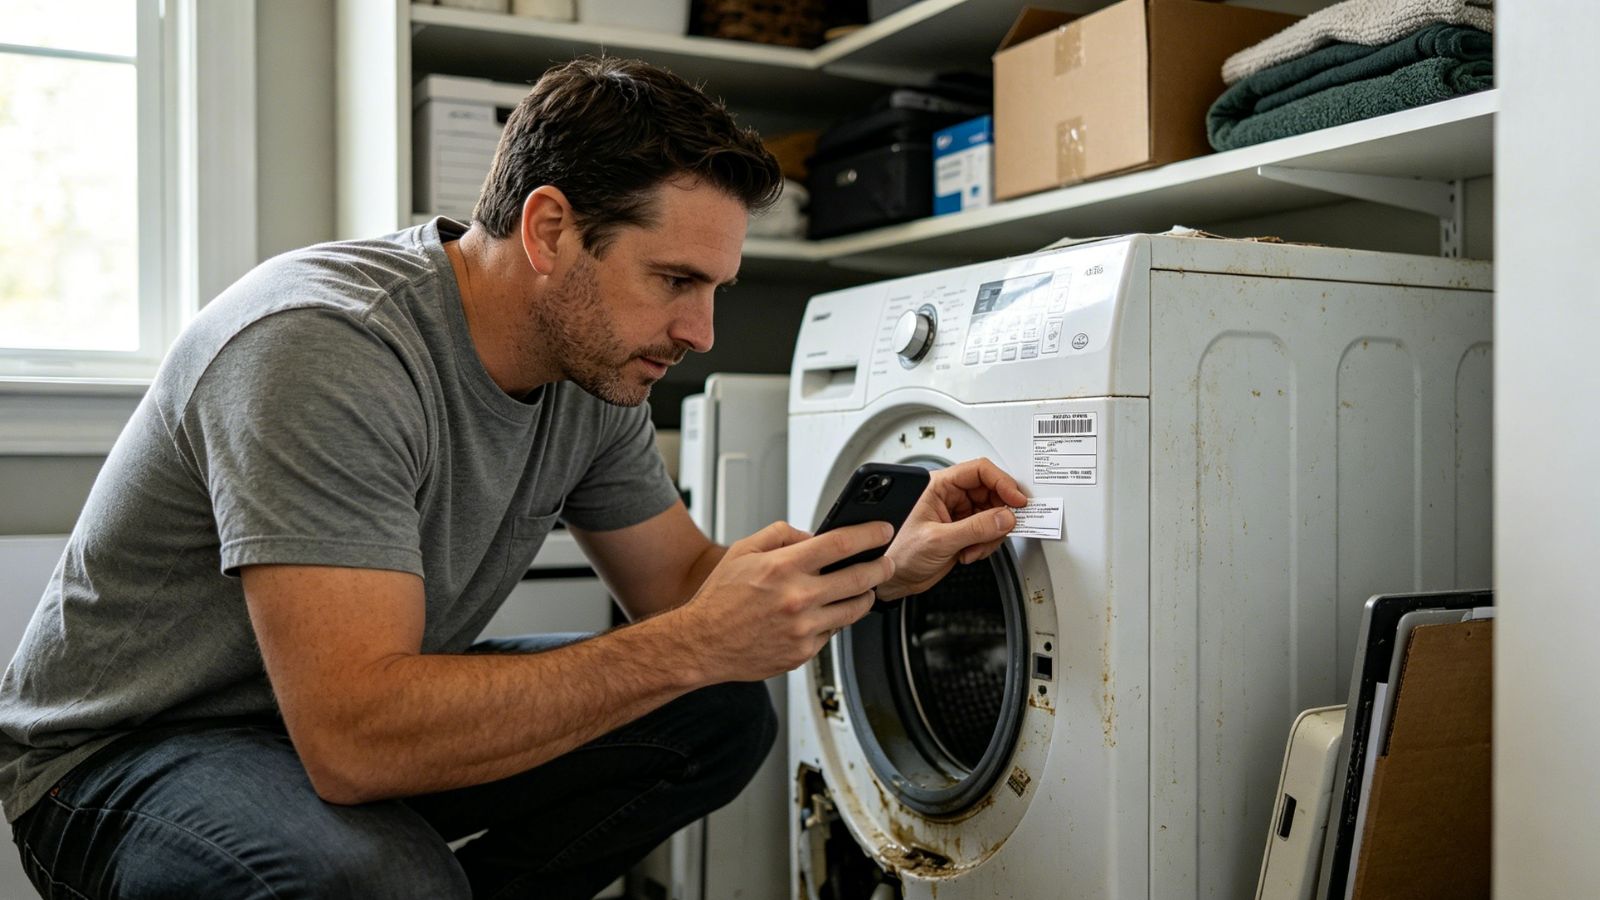
The absolute first priority following any catastrophic incident or property loss is personal and structural safety. Once immediate hazards have been safely addressed, documenting the original condition of the affected environment preserves vital physical information that may otherwise disappear forever during emergency cleanup, mitigation, or structural repairs. For property damage claims, high-resolution photographs and videos can successfully capture the exact location, physical extent, and structural nature of the damage before debris is cleared or compromised materials are removed. A truly useful visual record should seamlessly capture both the broader contextual environment and minute individual details. Wide-angle photographs establish precisely where the damage occurred within the property, while closer macro images highlight broken components, water stains, structural cracks, ruined finishes, or affected personal belongings. Photographing adjacent, undamaged areas can also provide critical spatial context for claims adjusters evaluating the shockwave or spread of an incident. Guidance from the Federal Emergency Management Agency (FEMA) under the National Flood Insurance Program explicitly emphasizes the value of detailed photographs and inventories that accurately document the quantity, quality, and physical extent of damaged property. Policyholders must also follow instructions regarding the preservation of damaged property. Temporary mitigation measures are frequently necessary to prevent secondary damage, but permanently repairing or discarding items before an adjuster has inspected them can severely complicate claim evaluation. The NAIC advises policyholders to photograph all damage prior to initiating repairs whenever safely possible and to retain damaged personal property for formal inspection.
Compiling a robust property inventory requires significantly more precision than relying on general summary statements such as "furniture and electronics were damaged." For each significant asset included in the claim, the supporting record should capture a detailed item description, exact quantity, approximate age, identifying information, purchase documentation when available, and the specific nature of the damage. While original purchase receipts are immensely helpful, they are certainly not the sole form of acceptable evidence. Depending on the exact nature of the claim, alternative records can include invoices, credit card statements, bank records, warranty information, product manuals, repair estimates, or prior home inventory logs. The NAIC recommends maintaining detailed, up-to-date home inventories that incorporate specific metadata such as brand names, purchase prices, exact acquisition dates, model or serial numbers, physical receipts, and photographs. The primary goal is to make every single claimed item reasonably identifiable and unambiguously connected to the reported loss. Utilizing a simple digital spreadsheet, a dedicated inventory application, or an organized cloud folder structure can dramatically streamline this process, particularly when a large volume of personal belongings is involved.
Medical and bodily injury claims require an entirely different category of evidence because the financial loss is tied directly to healthcare services and physical recovery rather than tangible property. Relevant documentation in this category includes formal medical bills, statements from healthcare providers, detailed treatment records, explanations of benefits from health insurers, pharmacy receipts, and records showing exact amounts paid out of pocket. It is critical to recognize the distinction between a healthcare provider's initially billed amount and the final negotiated figure a patient actually owes. Health insurance claims frequently involve complex cost-sharing mechanisms such as annual deductibles, copayments, coinsurance, negotiated provider rates, and policy exclusions. A medical billing statement on its own does not automatically establish the exact amount an insurance carrier will reimburse. Maintaining meticulous payment records helps establish true out-of-pocket expenses, with the NAIC specifically recommending that consumers retain physical receipts and bank statements showing direct payments for healthcare costs. For disputed health or personal injury claims, supporting medical evidence may also require diagnostic test results, imaging reports, or formal documentation from an attending physician explaining the medical necessity of specific treatments. Because medical documentation contains highly sensitive personal information, it must be handled with strict care, submitted only through designated secure portals, and backed up with private, organized local copies.
Many insurance claims involve auxiliary expenses that are exceptionally easy to overlook because they accumulate gradually after the initial incident has passed. Temporary lodging, emergency storage fees, immediate stabilization repairs, alternative transportation, and basic replacement necessities can all represent legitimate additional living expenses or business interruption costs depending on the governing policy terms. The safest and most reliable approach is to record these secondary expenses dynamically as they occur, rather than attempting to reconstruct months of receipts from memory. Policyholders should keep physical receipts, digital invoices, payment confirmations, and related supporting records grouped together alongside clear notes detailing the date and specific business or personal reason for each expense. The NAIC specifically advises consumers to maintain comprehensive records of all receipts associated with covered recovery expenses. A well-maintained expense record should explicitly distinguish between what was purchased, why the purchase was functionally necessary, when the acquisition occurred, and how much was paid. This qualitative context transforms a random stack of paper receipts into a persuasive financial narrative. However, documentation alone does not automatically guarantee that an expense is reimbursable; whether a particular cost qualifies depends entirely on the policy contract, the proximate cause of the loss, applicable sub-limits, and statutory requirements.
Evidentiary records extend far beyond physical photographs and financial receipts. Every official communication between the policyholder and the insurance carrier forms a vital part of the overarching claim file, which proves critical if questions, delays, or disputes arise later in the process. Policyholders should preserve copies of all incoming and outgoing emails, letters, submitted forms, contractor estimates, and formal correspondence. For telephone or in-person conversations, maintaining a contemporaneous log recording the exact date, time, representative's name or identification number, and a summary of the discussion is invaluable. The NAIC explicitly recommends keeping thorough records of all communications with an insurer, noting dates, times, and specific discussion topics. Furthermore, recording when documents were transmitted and the specific delivery method used prevents confusion and eliminates the frustrating cycle of repeatedly resending identical materials while overlooking a genuinely missing document.
A truly effective evidence collection system should make the entire insurance claim easy for any reviewer to understand from inception to final settlement. One practical organizational strategy is to partition records into clear, distinct categories: initial incident documentation, property damage inventories, medical expense files, auxiliary financial losses, professional estimates, and formal insurer communications. File naming conventions should be intuitive, incorporating dates and short descriptions rather than relying on generic default names like "IMG_4821" or "document2." Original photographs must be preserved in high fidelity, and redundant cloud backups of critical files should be maintained at all times. Above all, submitted evidence must remain scrupulously truthful and consistent. Policyholders must never alter photographs, inflate financial expenses, recreate missing documents to mimic originals, or claim absolute certainty about unknown facts. Insurance claims are adjudicated strictly on verifiable evidence, and inaccurate or falsified documentation creates systemic legal and administrative problems that extend far beyond a single disputed expense.