
When an insurance claim involves significant property damage or complex financial losses, one of the first unfamiliar figures a policyholder encounters is an insurance adjuster. Adjusters investigate losses, examine relevant records, inspect damaged property, and assist in determining the amount payable under an insurance contract. However, not every adjuster works for the same party, and understanding these professional distinctions is essential for navigating the claims process effectively. In the United States, the terms staff adjuster, independent adjuster, and public adjuster describe fundamentally different relationships to the claim and the parties involved.
The distinction matters because an adjuster's professional role dictates whom that person ultimately represents during negotiations. Staff adjusters and independent adjusters generally work on behalf of the insurance carrier, while a public adjuster represents the policyholder. Because state licensing requirements and specific regulatory rules vary widely across jurisdictions, terminology and procedural expectations can differ from state to state. Understanding these distinct roles makes it much easier to know who is handling a claim, what specific information they are seeking, and when retaining additional professional assistance may be appropriate.
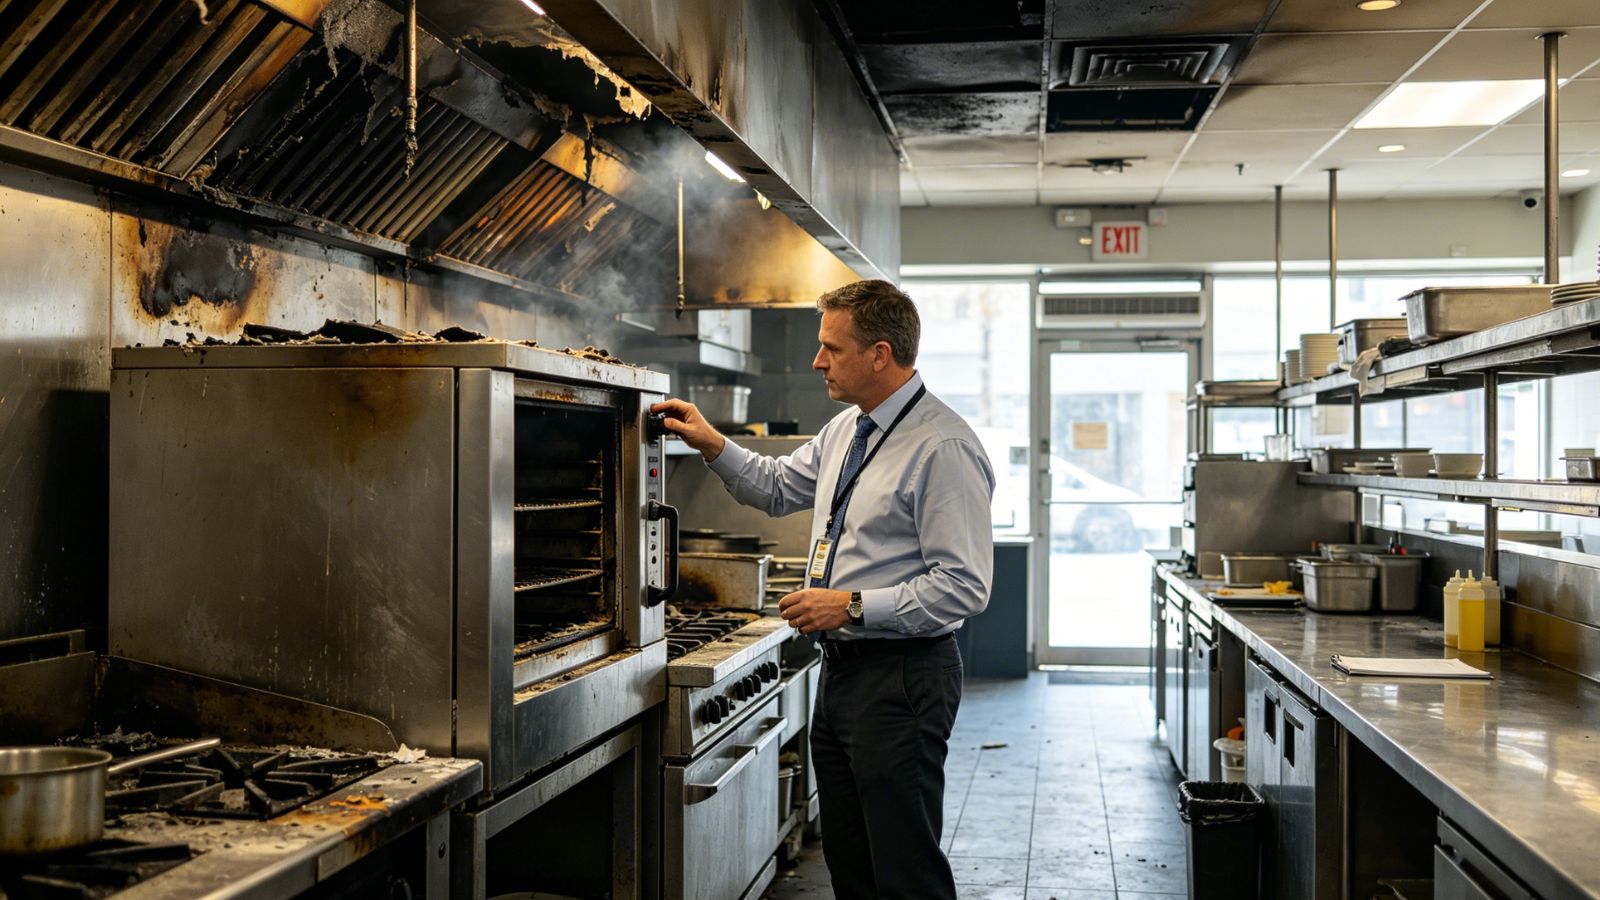
A staff adjuster, frequently referred to as a company adjuster, is a salaried employee of the insurance company or one of its corporate affiliates. Guidance from the National Association of Insurance Commissioners (NAIC) describes staff adjusters as internal professionals who exclusively adjust claims for their direct employer rather than for unrelated insurance entities. Because they work directly for the insurer, the policyholder does not separately hire, retain, or compensate the staff adjuster for handling the claim file.
An independent adjuster also represents the insurer, but the underlying employment and contractual relationship is entirely different. Independent adjusters are typically self-employed contractors or work for independent adjusting firms that are hired by insurance carriers to investigate, evaluate, or adjust claims on a contract basis. A single independent adjusting firm may handle claims for dozens of different insurance companies concurrently. The word "independent" can easily mislead consumers if it is interpreted as meaning independent of the insurer; in this professional context, the term refers strictly to the adjuster's business relationship as an outside contractor rather than any independent advocacy for the policyholder.
A public adjuster occupies the opposite side of the transactional dynamic. A public adjuster represents the insured rather than the insurance carrier, typically assisting with the meticulous preparation, presentation, detailed estimation, and negotiation of a first-party property claim. The policyholder directly hires the public adjuster and assumes full responsibility for the agreed-upon financial compensation, which is usually structured as a percentage of the final insurance payout. The NAIC model framework explicitly classifies public adjusters as specialized licensed professionals acting exclusively on behalf of insureds in complex property claims.
Evaluating who an adjuster represents requires looking beyond a friendly demeanor or the corporate logo on a business card. The defining factor is who hired or employs the adjuster and whose financial and legal interests that individual is authorized to protect.
Staff adjusters are corporate employees whose primary loyalty and compensation flow directly from the insurance carrier. Their evaluations are guided by internal company guidelines, policy definitions, and corporate loss-adjustment philosophies. Independent adjusters operate as external contractors hired by the insurance company. While they maintain technical independence from the insurer's internal hierarchy, their contractual obligations and financial incentives remain tied to satisfying the hiring insurance carrier.
Public adjusters operate under a completely inverted model. They are retained directly by the policyholder through a formal binding contract, paid directly by the policyholder, and legally obligated to advocate for the policyholder's financial interests throughout the claim lifecycle. State laws heavily regulate public adjusters, imposing strict licensing prerequisites, disclosure rules, and maximum fee caps to protect consumers during vulnerable moments.
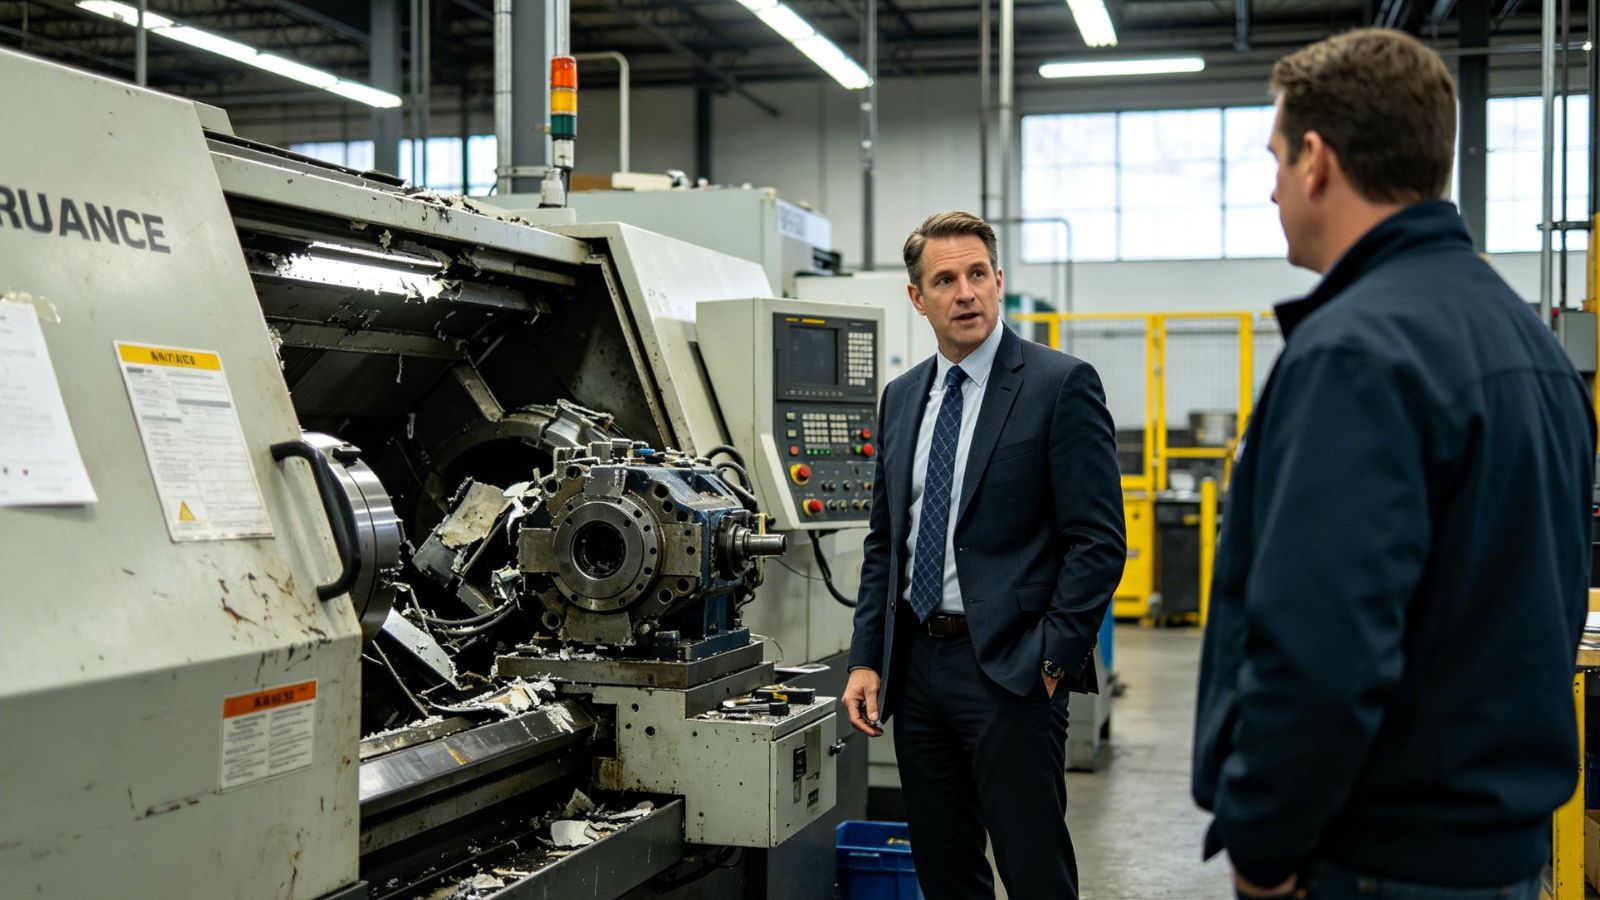
After a formal claim is reported, the insurer assigns an adjuster to investigate the underlying loss. Depending on the scale of the damage, that investigation involves visiting the property, examining ruined items, reviewing photographic evidence, obtaining contractor estimates, and analyzing the governing policy provisions. For instance, NAIC consumer guidance notes that an insurer's adjuster routinely inspects a home and damaged property shortly after a reported loss occurs.
An adjuster's job extends far beyond simply snapping photographs and generating a basic repair estimate. A comprehensive claim investigation requires answering several core questions: What actually happened? When did the event occur? What specific property was affected? What was the proximate cause of the damage? Which portions of the loss fall within the defined scope of coverage? What deductibles, aggregate limits, exclusions, or endorsements affect the final payout?
This reality highlights why policyholders must distinguish between documenting a loss and proving that the insurer is legally obligated to cover it. Photographs, receipts, repair estimates, and inventories help establish factual reality, but they do not override the language of the insurance contract. Coverage ultimately depends on the precise wording of the policy and applicable state laws.
For a policyholder navigating an active claim, the practical differences between a staff adjuster and an independent adjuster are often less significant than they initially appear. Both categories of adjusters ultimately represent the insurer's interests throughout the adjustment process.
A staff adjuster handles claims as part of an insurance company's internal operations, whereas an independent adjuster is brought in when an insurer requires outside surge capacity following a major natural catastrophe or lacks internal staffing in a specific geographic region. NAIC licensing guidelines explicitly recognize that independent adjusters possess the authority to investigate, negotiate, and settle claims on behalf of insurers.
For consumers, the label "independent" should never be interpreted as a guarantee of absolute neutrality or impartiality. An independent adjuster can be an outside contractor while remaining firmly aligned with the insurer's financial interests. Catastrophe situations further complicate this dynamic, as large-scale weather events generate massive waves of claims, prompting state licensing frameworks to activate special emergency provisions for nonresident independent adjusters.
A public adjuster fundamentally changes the representation structure of a claim because they are hired and paid directly by the policyholder. A public adjuster can assist with organizing the claim file, documenting structural and personal property damage, preparing detailed independent estimates, communicating with insurer representatives, and negotiating the final settlement amount.
Hiring a public adjuster is never a mandatory requirement for filing or pursuing an insurance claim. The NAIC's regulatory framework explicitly acknowledges that every insured person retains the absolute legal right to handle a claim independently without professional representation. For a relatively straightforward claim with minimal ambiguity, a policyholder is often better served communicating directly with the insurer and managing documentation personally.
However, the calculation changes dramatically when a claim involves catastrophic property damage, extensive personal property loss, complex business interruption issues, or severe disagreements regarding the scope of required repairs. In those scenarios, the administrative and technical burden can become overwhelming, making the services of a qualified public adjuster worth evaluating. Policyholders must carefully review any proposed fee agreement, ensuring they fully understand the compensation structure, cancellation terms, and the exact scope of authority granted to the adjuster.
Insurance adjusters perform similar investigative tasks on the surface, but their professional relationships and loyalties are fundamentally different. Staff adjusters and independent adjusters work for the insurer, while public adjusters work exclusively for the policyholder.
Recognizing this distinction prevents common and costly misunderstandings during the claims process. An adjuster who operates independently of an insurance company's payroll is not necessarily independent of the insurance company's financial interests. For consumers, the most effective approach is to identify who the adjuster represents, understand the scope of the investigation, preserve pristine supporting evidence, and review the policy contract thoroughly before making assumptions about what an insurance claim should ultimately yield.